|
||
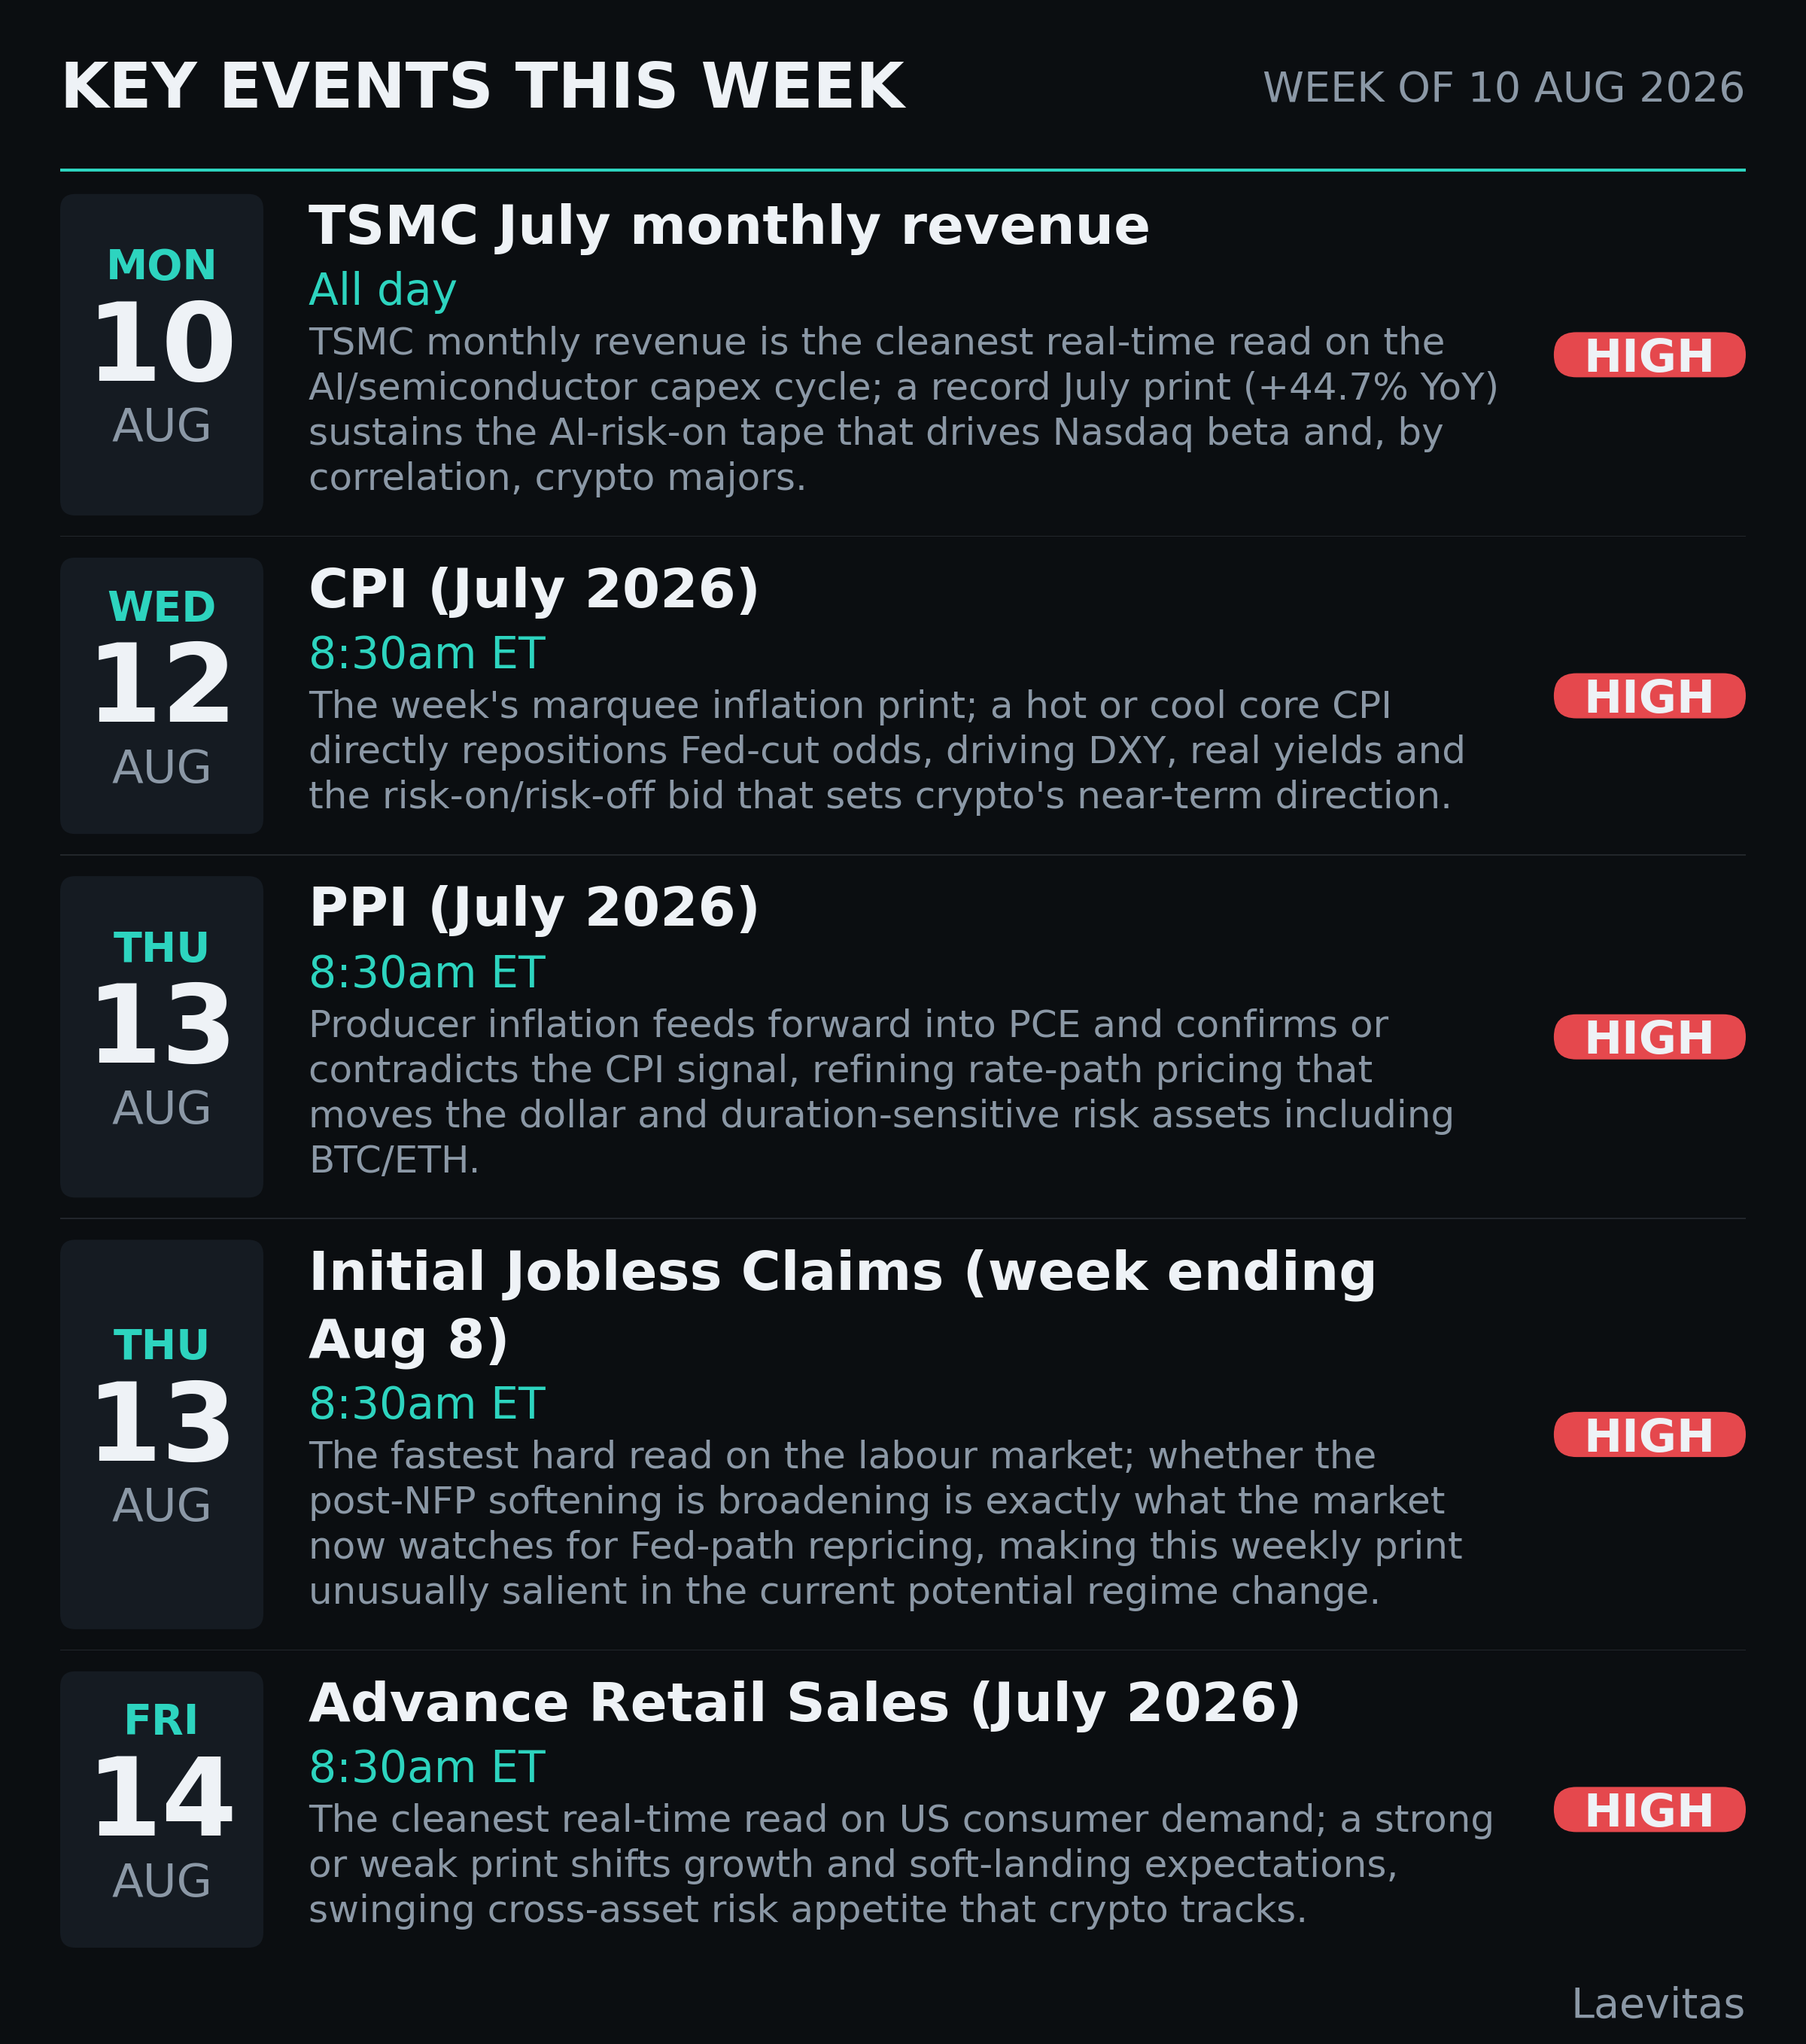
The Monday Brief // 10Aug26Rick @scopicview - Head of Markets, Laevitas Last week’s flagged pivot - the prospect of clearer guidance on the Fed’s reaction function after a light-touch July meeting - failed to resolve, and the long end held onto its cheapening as the reflation and steepening impulse carried into the new week. That leaves US July CPI on Wednesday as the week’s fulcrum, landing against a rates backdrop already stretched to multi-year extremes and a central-bank complex still declining to ease. The dollar channel is load-bearing for crypto here, and a single inflation print sits astride it. Key events this week
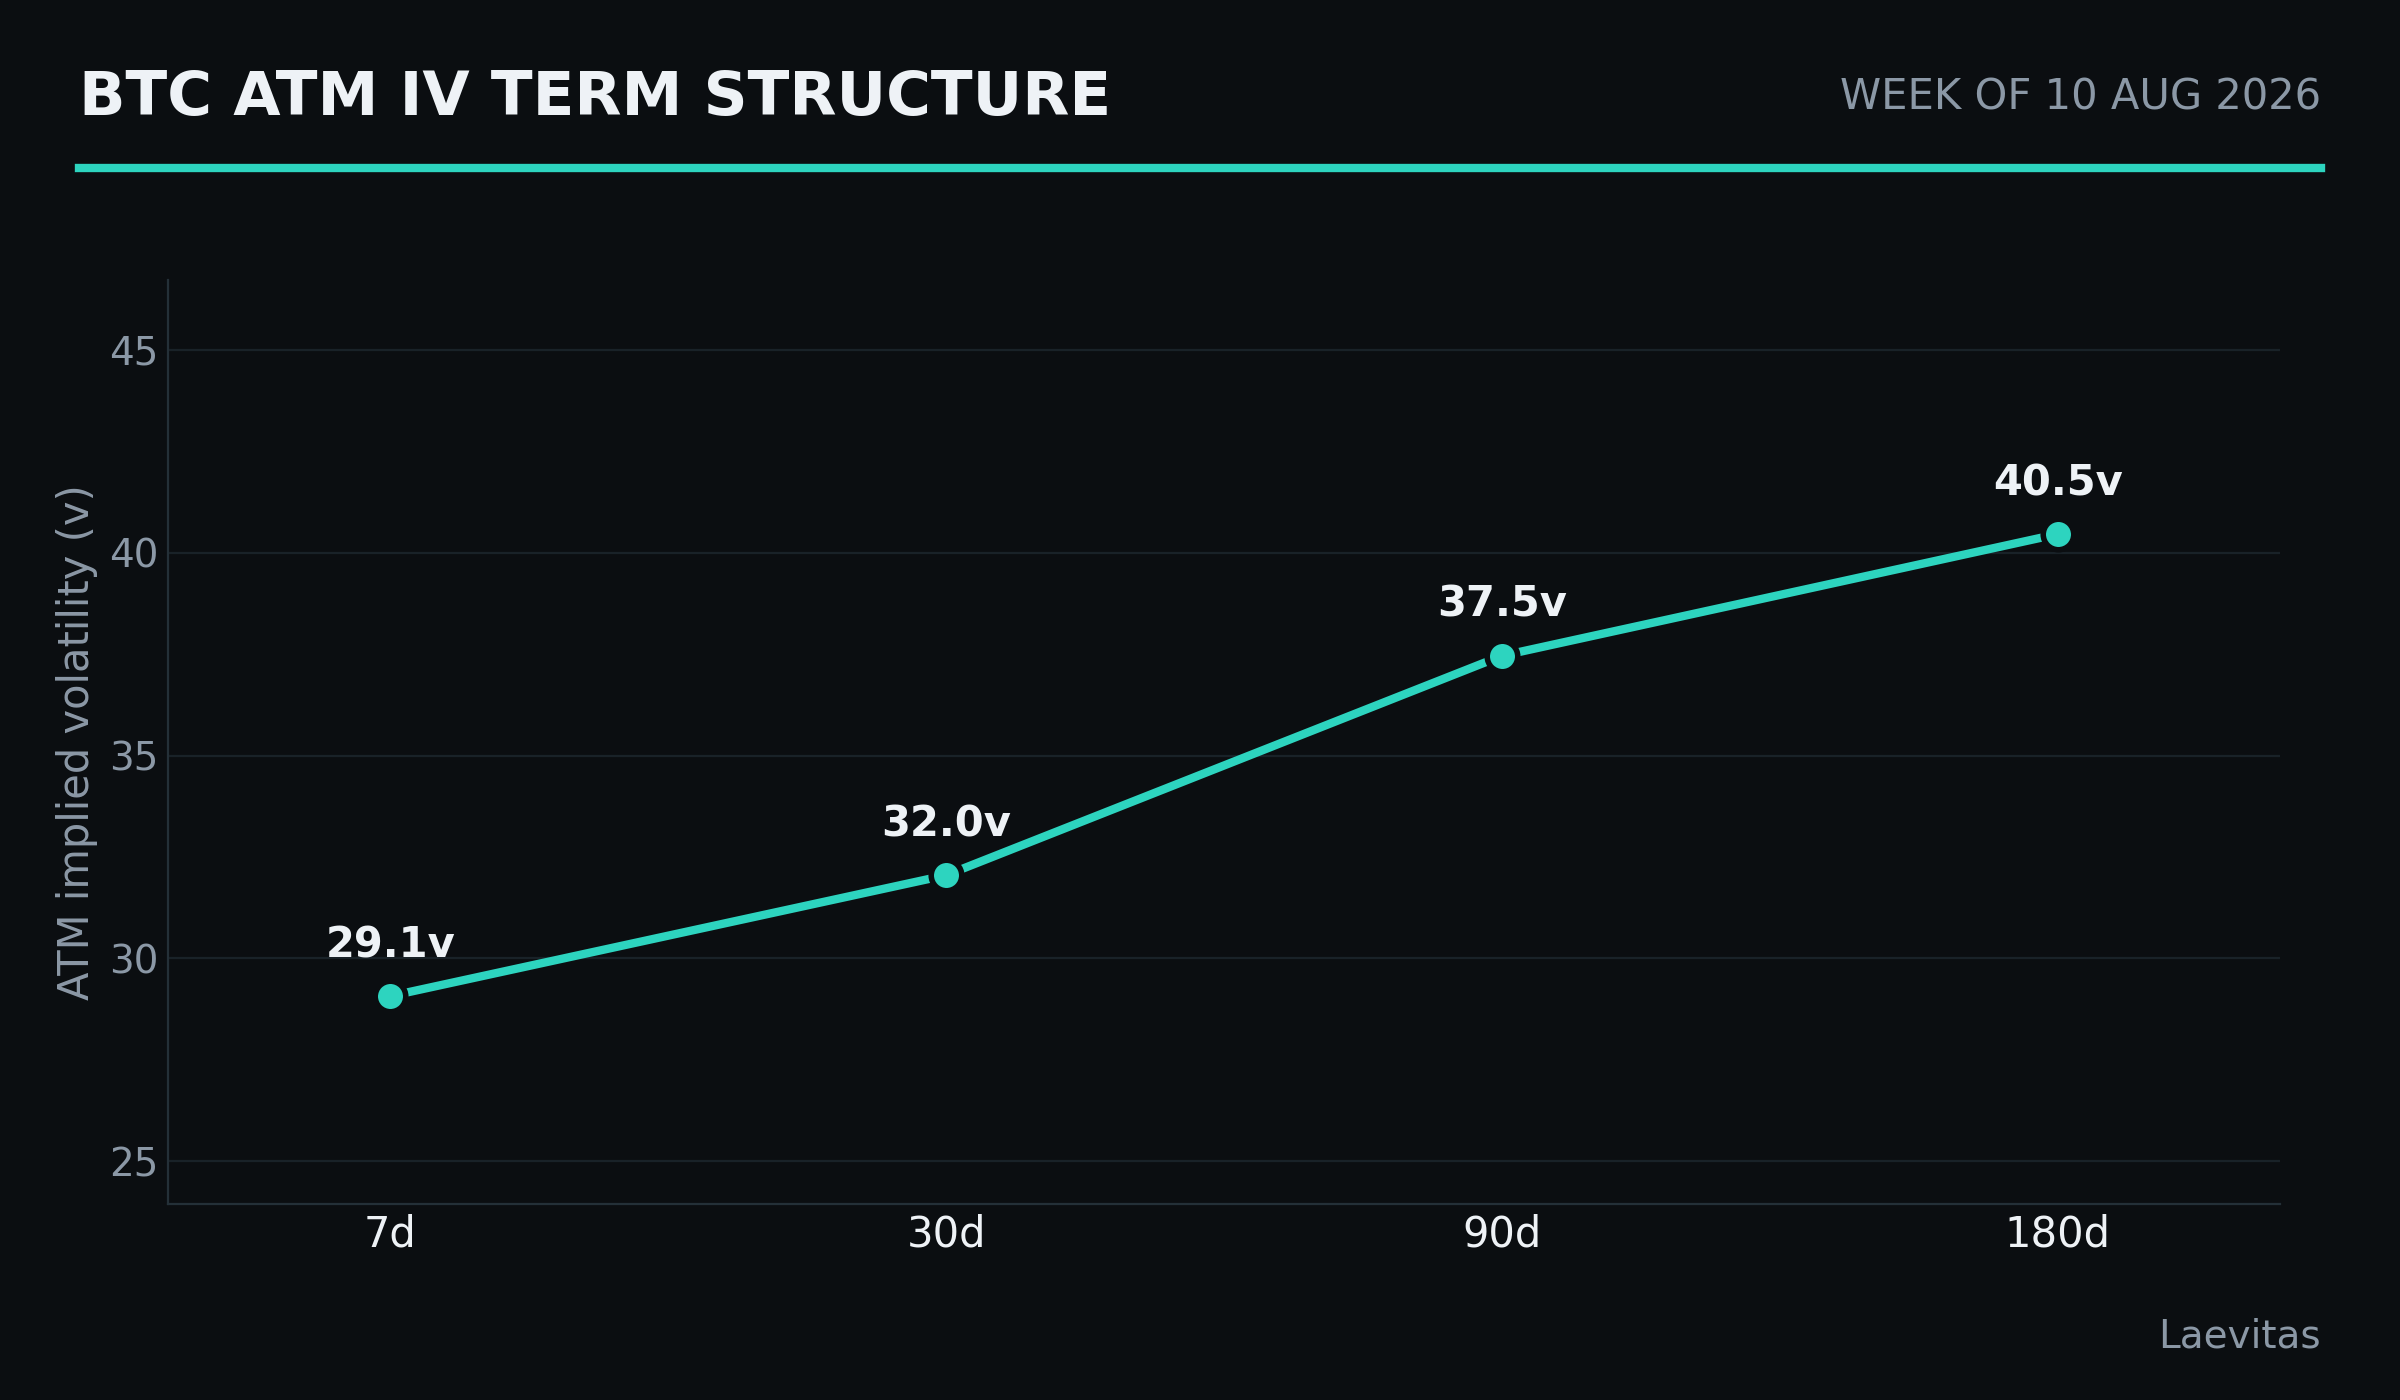
MacroThe July CPI release is the fulcrum for cross-asset positioning. Core is forecast to re-accelerate to +0.26% MoM from an unchanged June, headline to +0.15% after June’s -0.42% decline, with PPI following on Thursday. June’s soft core reading was one of the few supportive macro inputs in an otherwise hostile July tape and contributed to the dollar’s broad decline against every G10 currency; a firm July print validates the long-end’s anxiety and hardens the higher-for-longer regime, while a soft one extends that USD softness and reprices the front end lower. For high-beta crypto the release matters mainly through the dollar and the shape of the curve it sets. The long end is where the discomfort is concentrated. The 30-year Treasury closed July at 5.27%, a post-2007 high, and the 10-year at 4.74%, with the move reading as twist steepening carrying an uncertainty and credibility premium around the Fed’s reaction function rather than a clean repricing of growth or inflation. That policy-credibility discount may prove stickier than a single CPI undershoot can unwind. The picture rhymes across G3: the ECB signalled a probable September hike and drove the 10-year Bund to a post-2011 high near 3.20%, while the Bank of England was the dovish outlier. The easing tailwind crypto habitually leans on is simply absent from this configuration, and some pricing now entertains a resumption of Fed hikes later in the second half. Two forces keep the reflation read two-sided. Oil ran from roughly $71 to just over $100/bbl by 23 July on US-Iran re-escalation before retreating to about $90 into month-end, a +23.6% monthly gain, and the more recent signals lean toward fade rather than extension even as the current level stays genuinely uncertain; a de-escalation headline would deflate the inflation impulse and relieve duration and crypto alike. The tech tape is the second: a violent July AI and semiconductor de-rating, with the Philly Semiconductor index down 20.6% in its worst month since 2008, collided with exceptionally strong Q2 earnings and record breadth, leaving crypto to track Nasdaq and AI risk-appetite swings; TSMC’s July revenue today and the week’s semiconductor-equipment results are the next empirical test of the capex cycle. Monday’s BoJ Summary of Opinions is the acute near-term risk, the first read on whether July’s tightening rhetoric hardened after intervention rescued the yen from its weakest level since 1986, and the variable most able to reprice carry and echo the August-2024 unwind. CryptoThe vol surface has quietly de-risked into the catalyst. Front-end implied has compressed even with a binary CPI print inside the weekly window - $BTC 7d ATM IV eased from 32.1v to 29.1v and $ETH from 46.4v to 41.2v week-on-week - and the term structure holds its normal upward slope, 7d 29.1v against 90d 37.5v and 180d 40.5v on $BTC and 7d 41.2v against 90d 51.2v on $ETH, declining to kink for the event. On the IV-RV construction 7d realised sits well under implied, $BTC 21.5v realised against 28.3v implied and $ETH 28.3v realised against 40.4v implied, so realised has stayed subdued and the weekly premium into Wednesday looks contained relative to the catalyst carried on the tape.
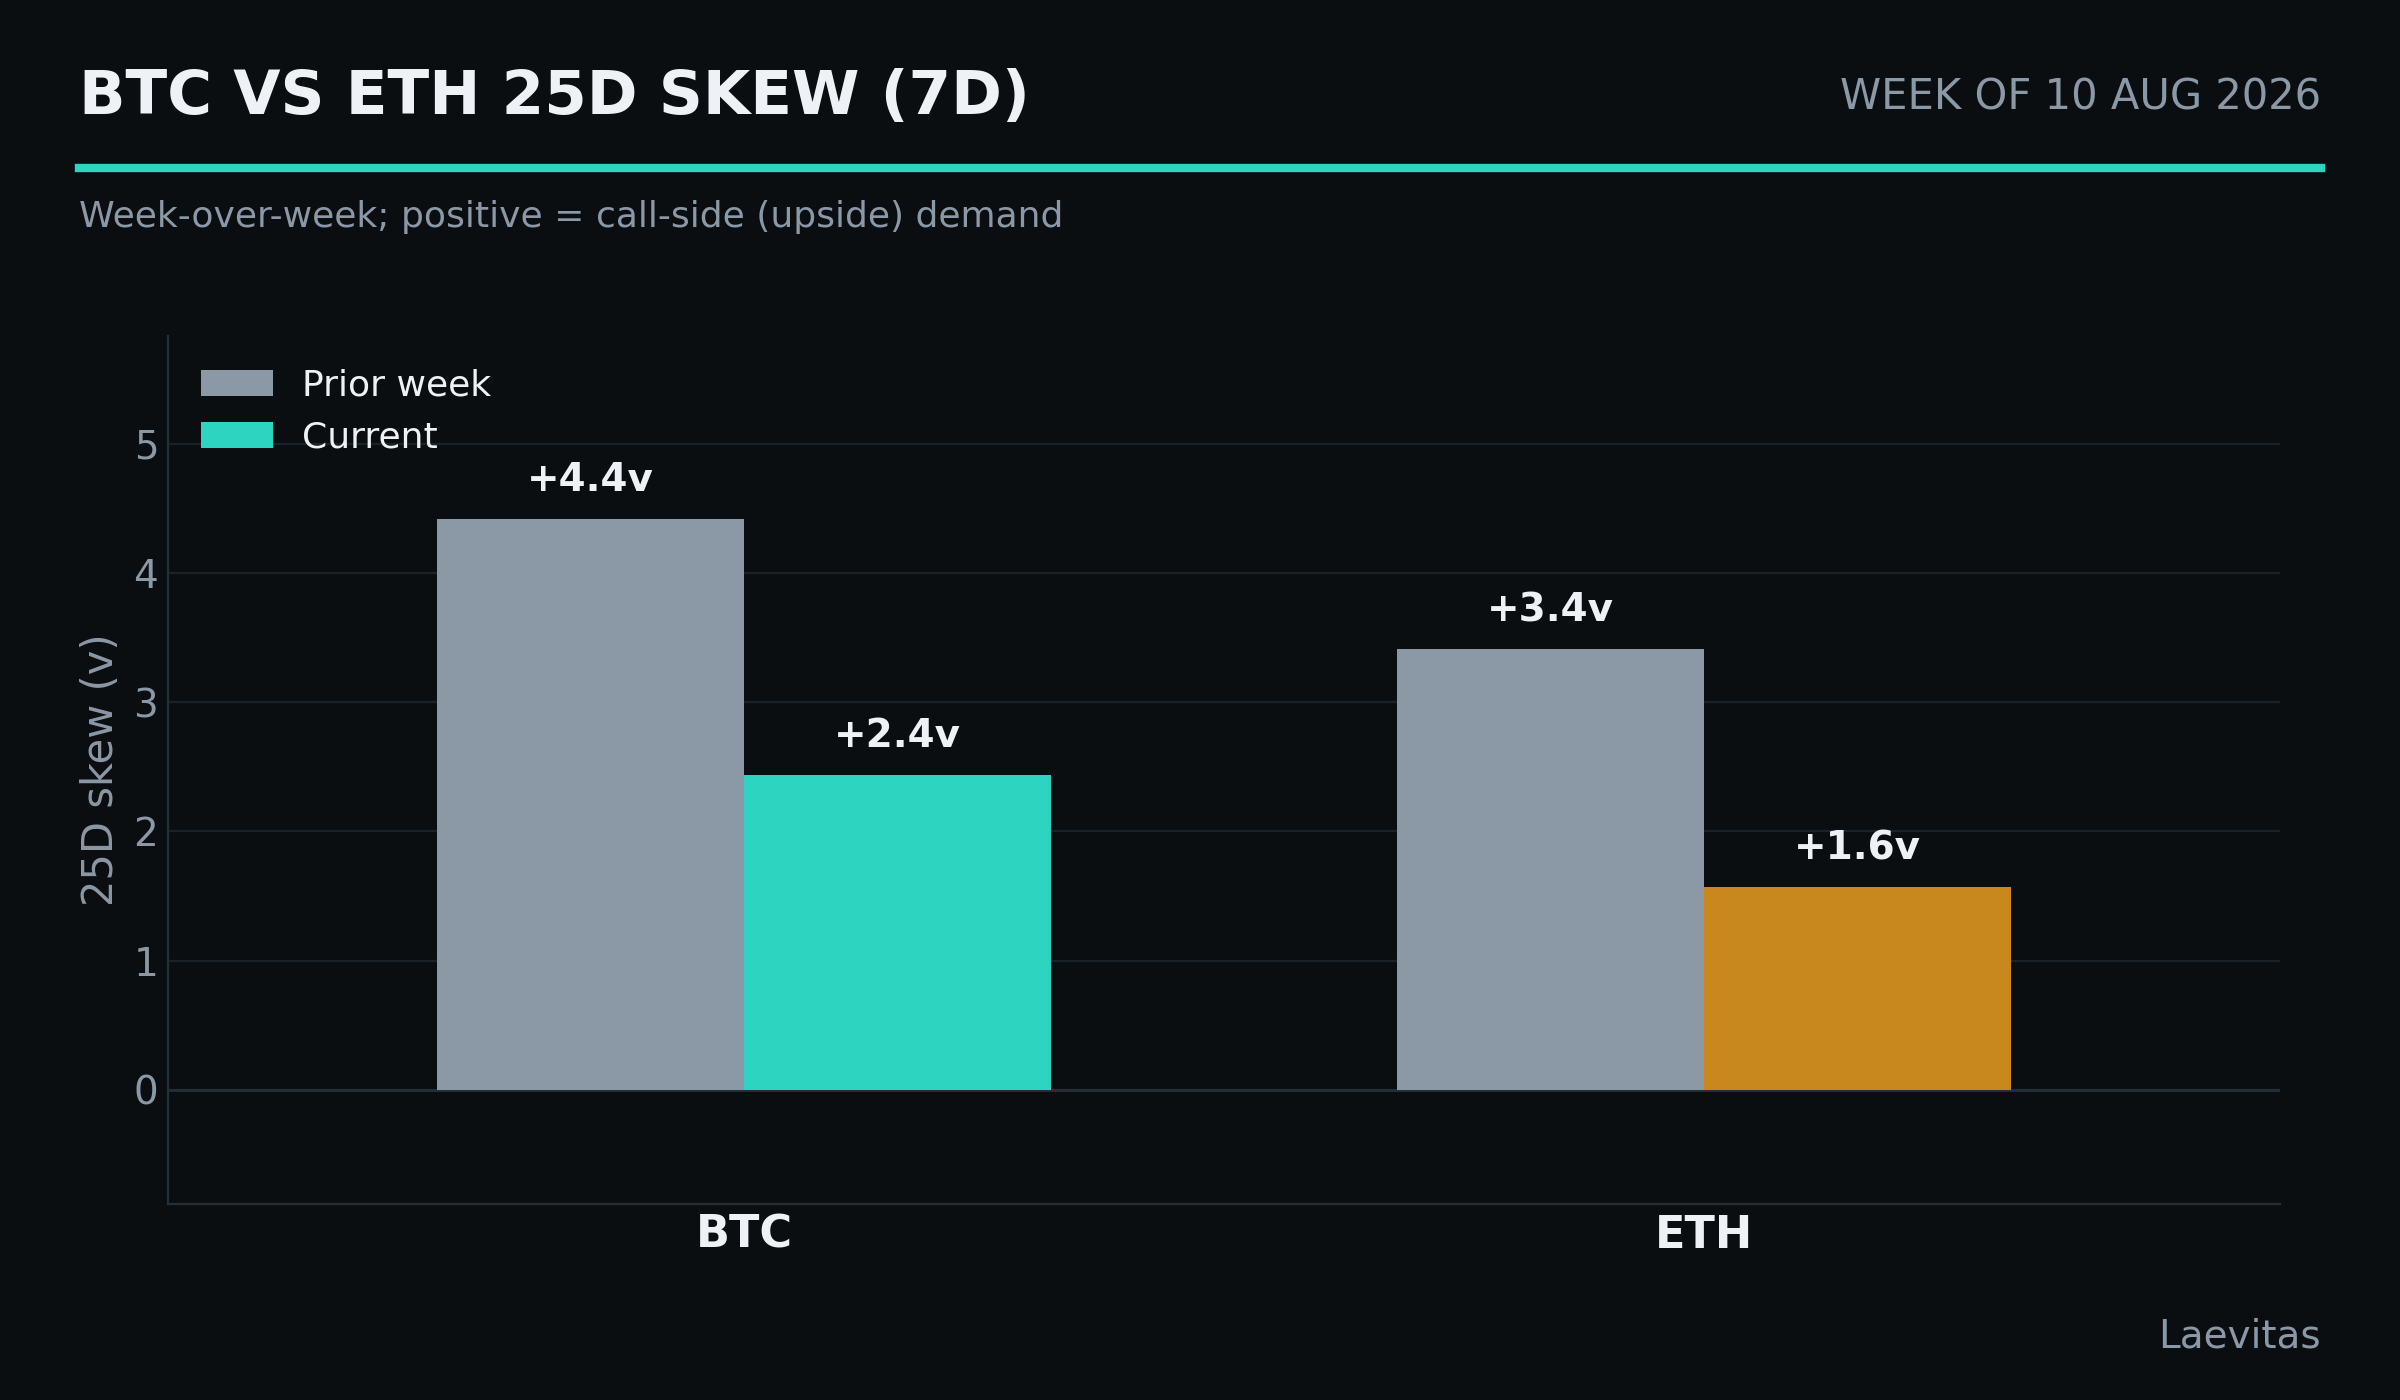
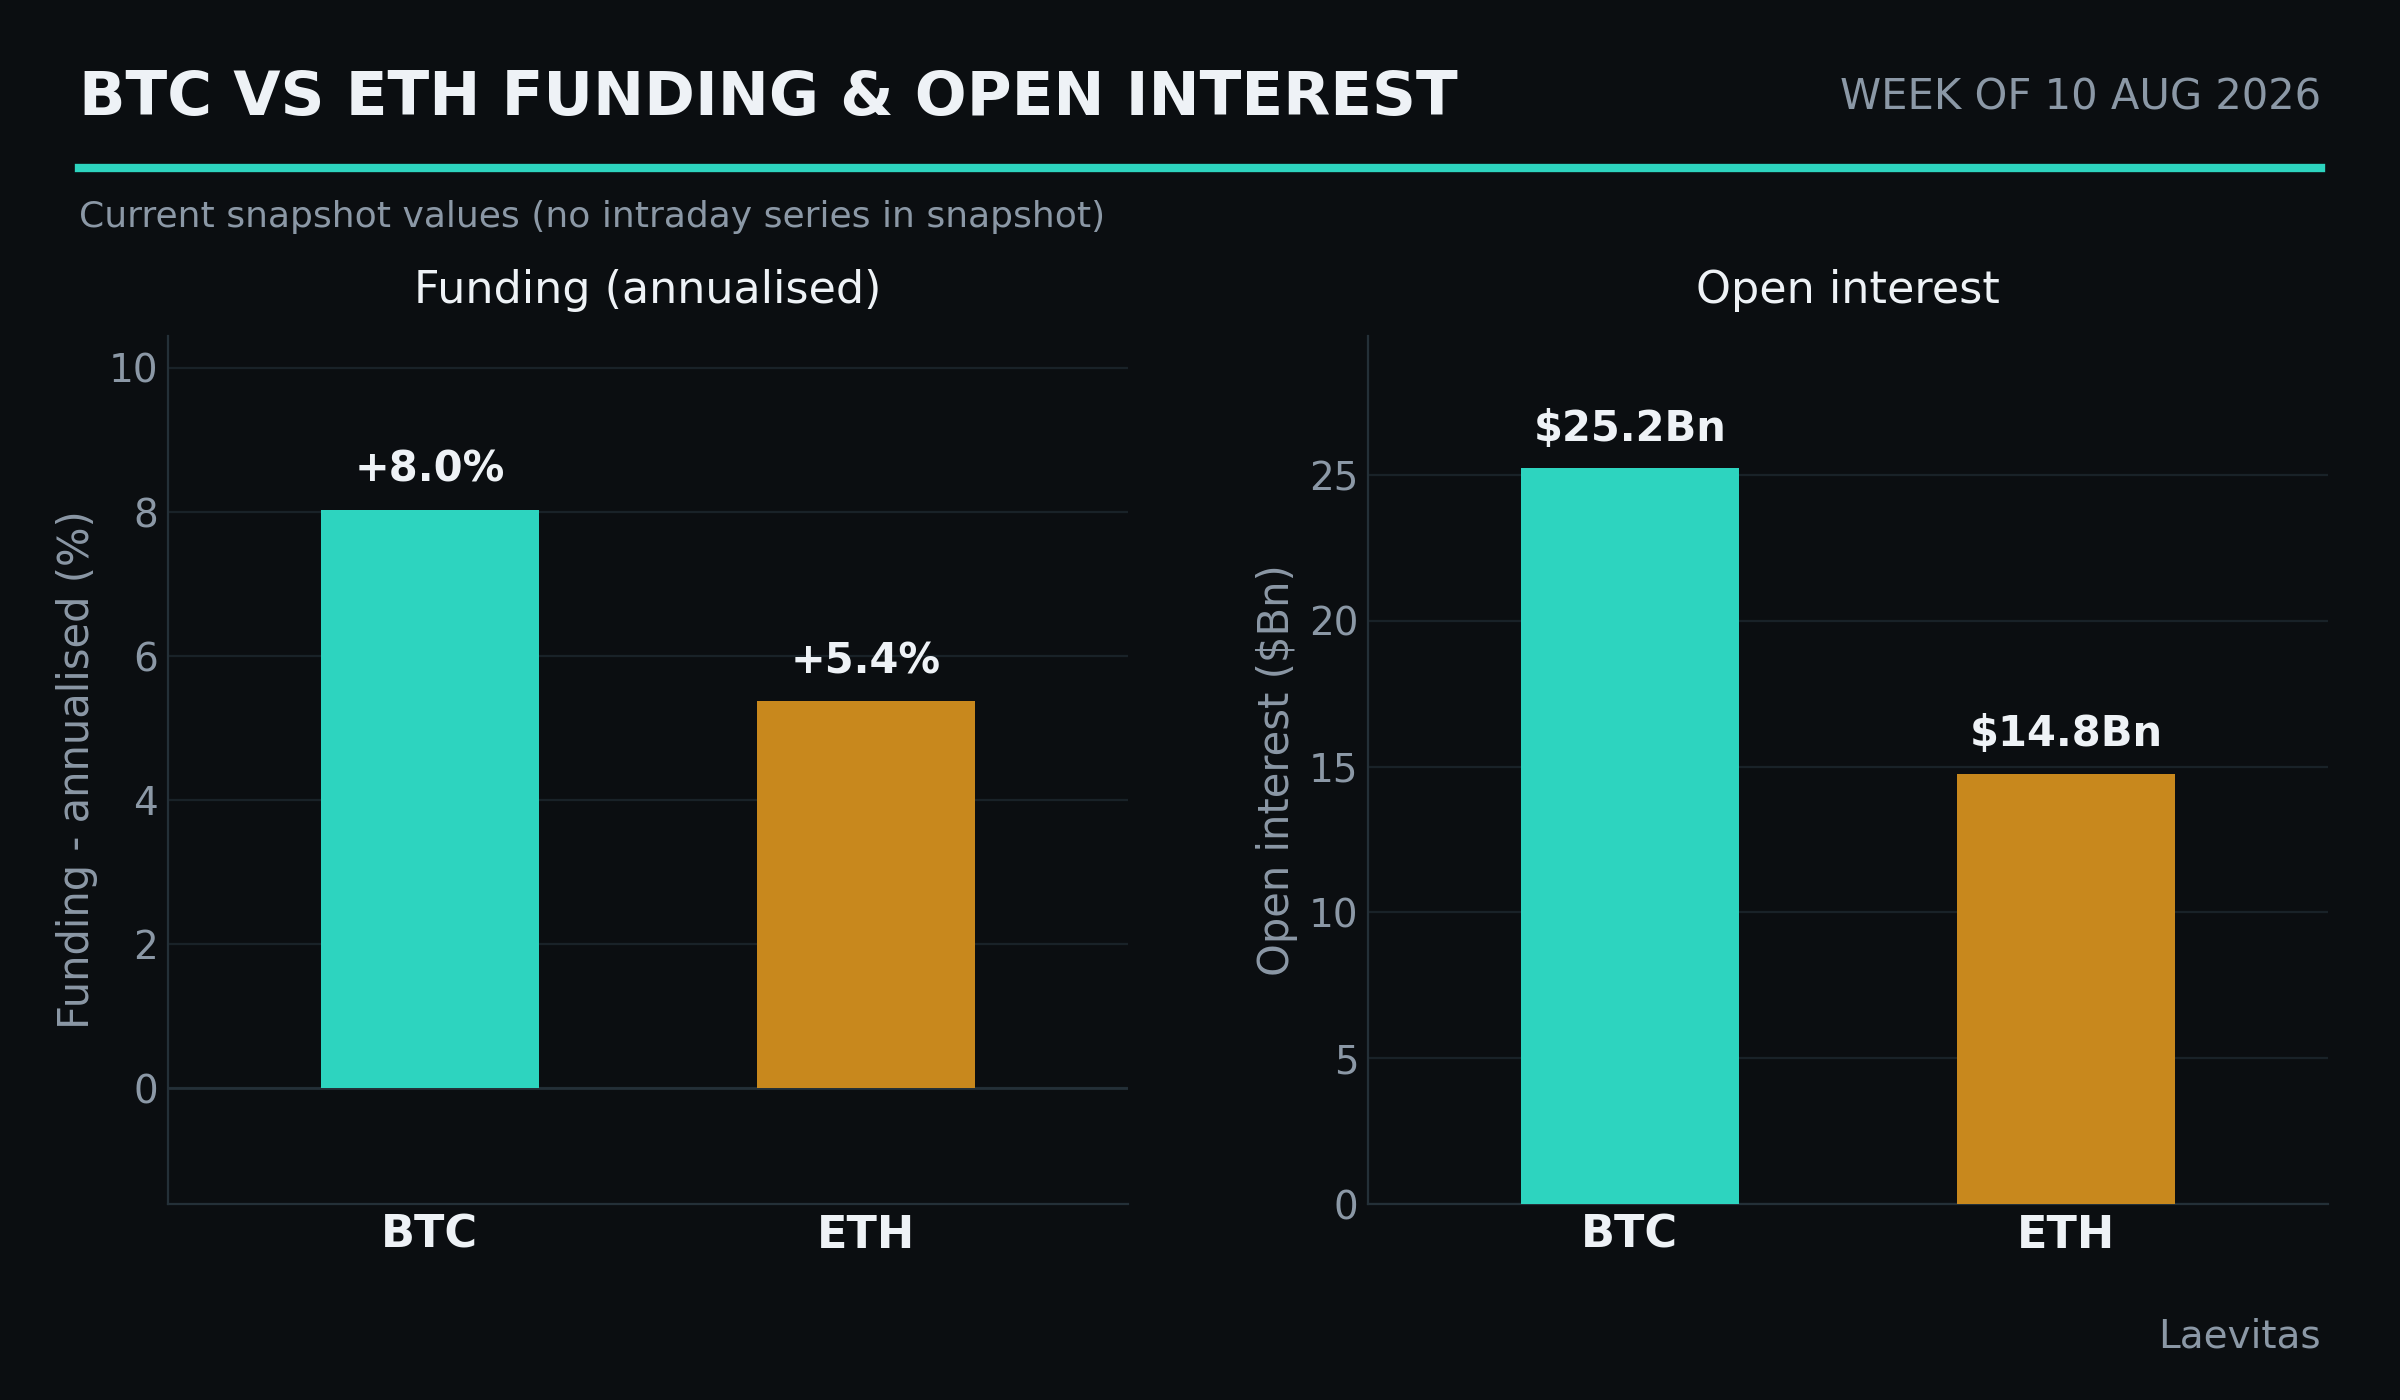
The clearest move on the surface is in skew. The 25D 7d risk reversal compressed from about +4.4v to +2.44v on $BTC and from about +3.4v to +1.57v on $ETH in a week, a marked bleed in the topside bid that leaves only a mild residual call premium across both names. Perp funding firmed off low levels, $BTC to roughly 8.0% annualised and $ETH to 5.4%, with open interest at $25,229MM on $BTC and $14,764MM on $ETH; the carry reads as modestly positive, with $BTC account positioning tilted toward shorts at a 0.69 long/short ratio while $ETH holds a mild long lean at 1.11.
The tension for the week is a vol surface that has quietly softened, with compressed front-end IV and a faded call bid, sitting in front of a July CPI print the research points toward re-accelerating and inside a central-bank regime still holding the front end firm; the higher-for-longer outcome that a firm core reading would validate remains the cleanest risk-off vector for high-beta crypto as it transmits through a firmer dollar and a cheaper long end, while a soft print that extends July’s dollar slide would relieve duration-sensitive risk, leaving direction contingent on which channel the release activates and whether the long end confirms the move. Positioning into the week
Week ahead | 2026-08-10 | Derivatives via Laevitas |
||
|
You are receiving this because you subscribed to the Crypto Derivatives Briefs at laevitas.ch. Laevitas SA, Switzerland. Unsubscribe · Privacy |