|
||
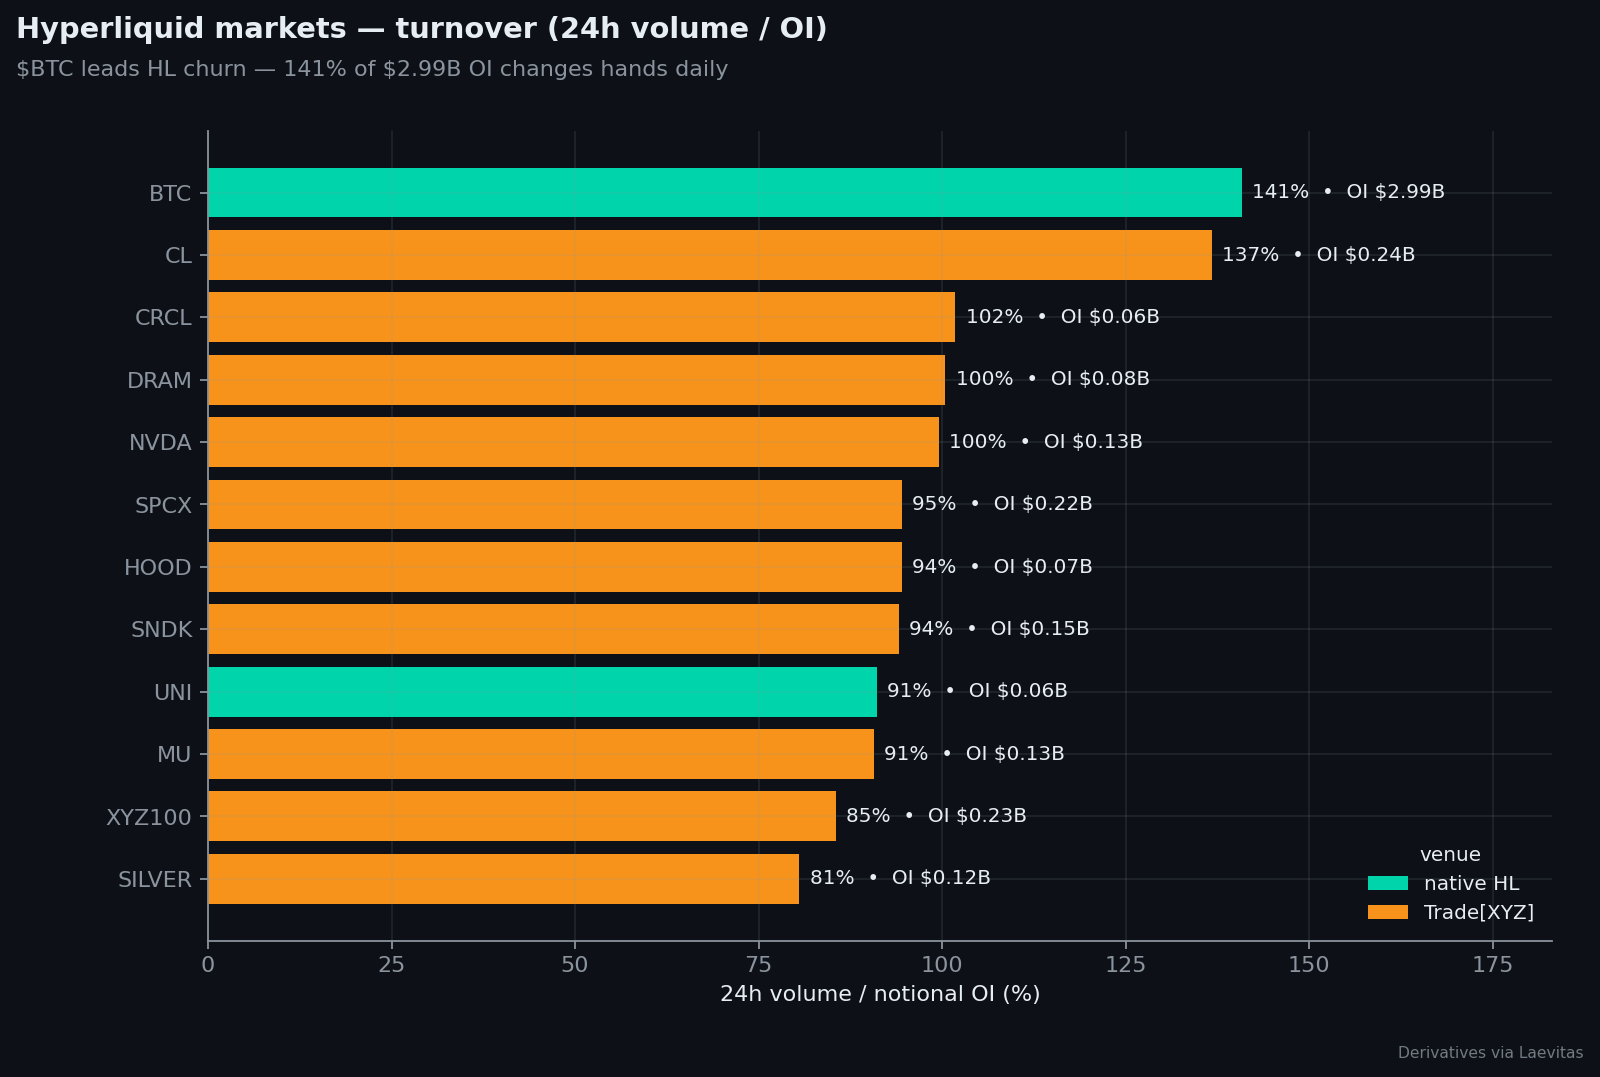
Midweek Hyperliquid Report // 03Sep26The heaviest churn on Hyperliquid this week sits in @tradexyz crude: xyz:CL turns 137% of its $0.24B of OI every 24h, second only to $BTC at 141% of $2.99B, and it does so while the shorts pay 63.9% annualised to keep the position on; Brent alongside it pays 51.4%. (i) Forced flow (ii) Funding and the algo tape (iii) HIP-3 builder markets
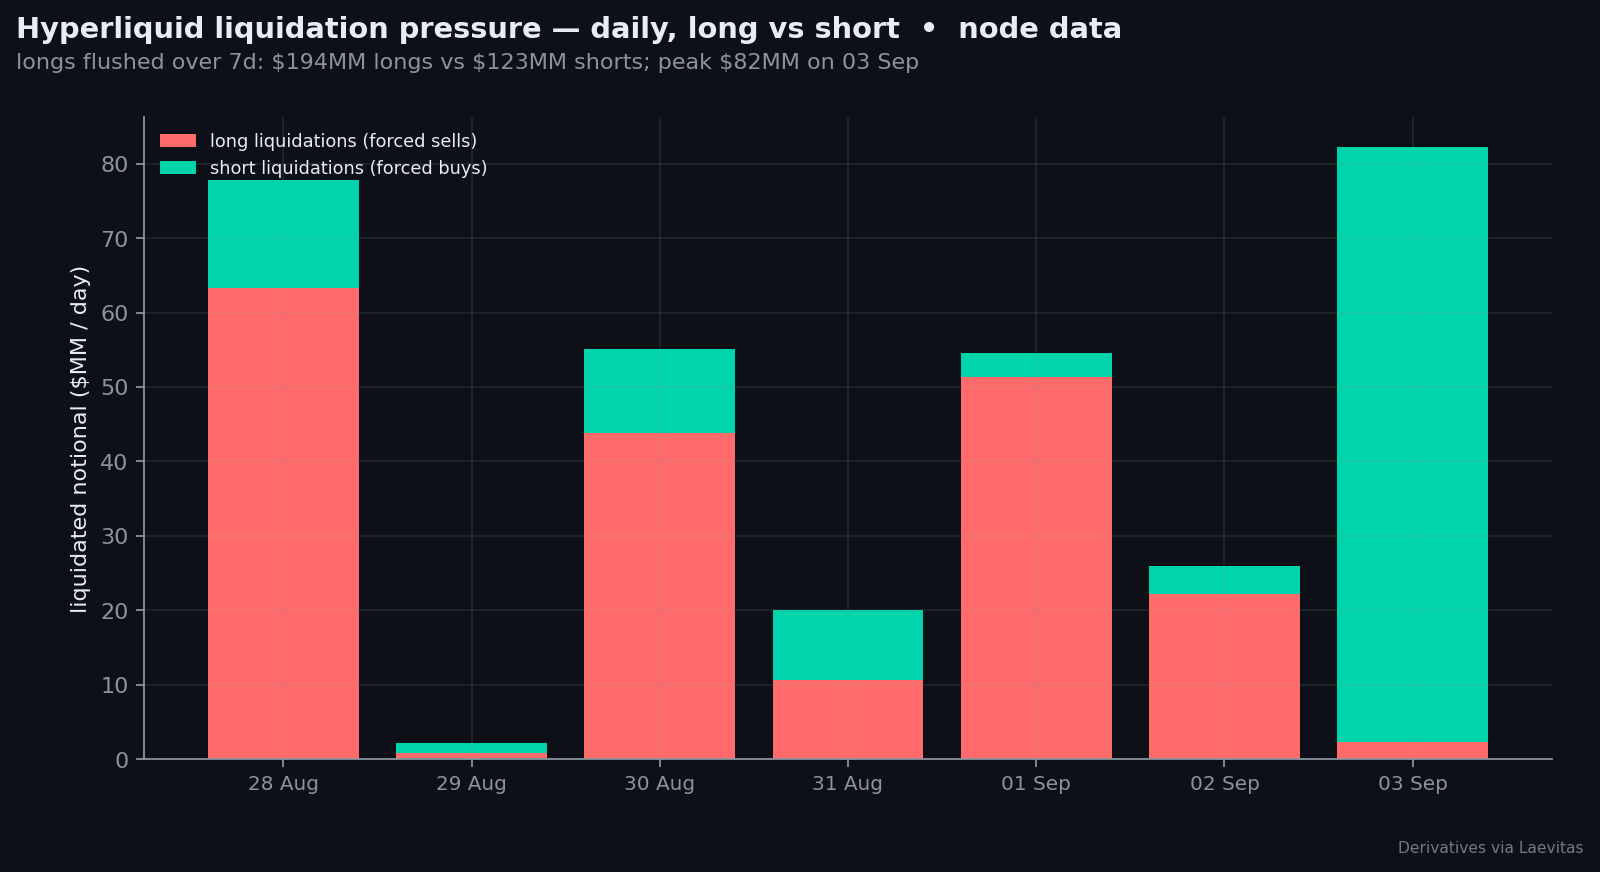
Forced flowForced flow ran in both directions this week, $194MM of longs against $123MM of shorts over 7d, and the largest single session was 3 September at $82MM, almost all of it forced buying as shorts were carried out. 1 September was the mirror image, roughly $51MM of longs against $3MM of shorts.
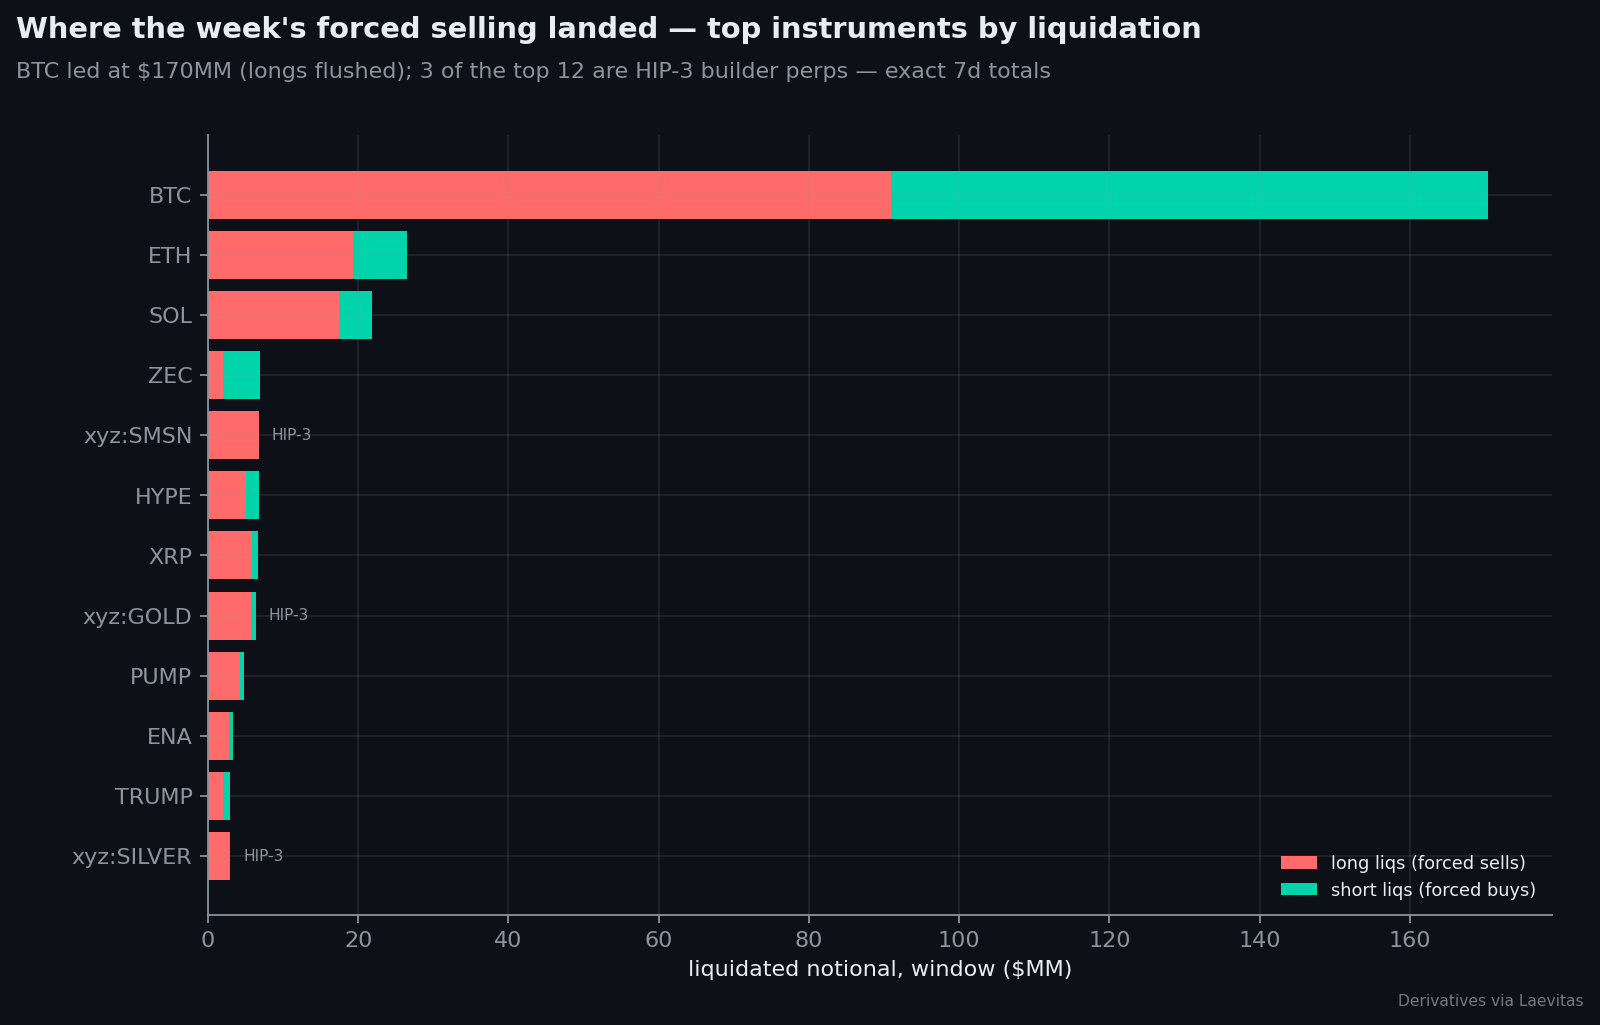
$BTC absorbed $170MM of the week’s liquidations, split roughly $91MM of longs against $79MM of shorts, with $ETH at $26MM and $SOL at $22MM behind it. Three of the top twelve are @tradexyz builder perps, xyz:SMSN at about $7MM, xyz:GOLD at $6MM and xyz:SILVER at $3MM; the crude book appears nowhere on the list.
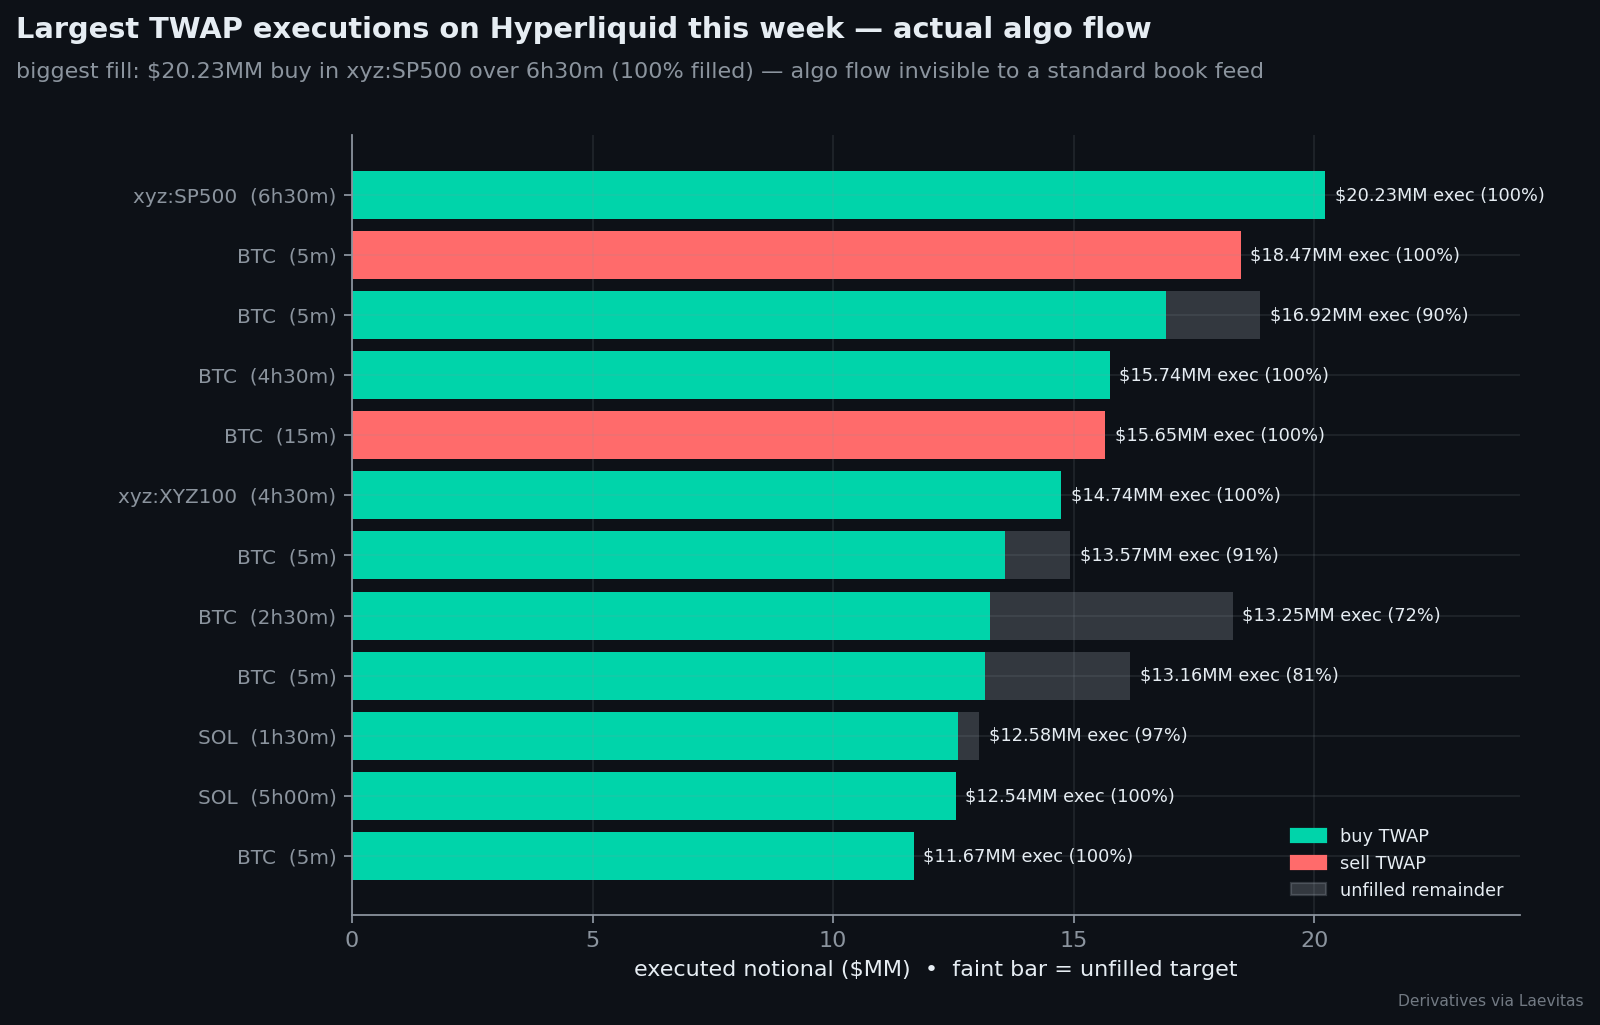
FundingNative HL funding sat at its defaults through both flushes, $ETH and $SOL at 10.9% annualised and $BTC marginally negative at -0.8%, while the builder books ran unarbitraged: NBIS pays 21.4% on @tradexyz against 114.8% on EntropyIO for the same underlier. The io book carries $7.4MM of OI against @tradexyz’s $67.5MM, so depth is what keeps that spread open. The algo tapeThe algo tape leaned to the buy side, with ten of the twelve largest TWAPs on the venue this week executing as buys, headed by a $20.23MM purchase in xyz:SP500 filled in full over 6h30m. The largest sell was an $18.47MM $BTC programme; two $BTC buys stopped at 90% and 72% of target.
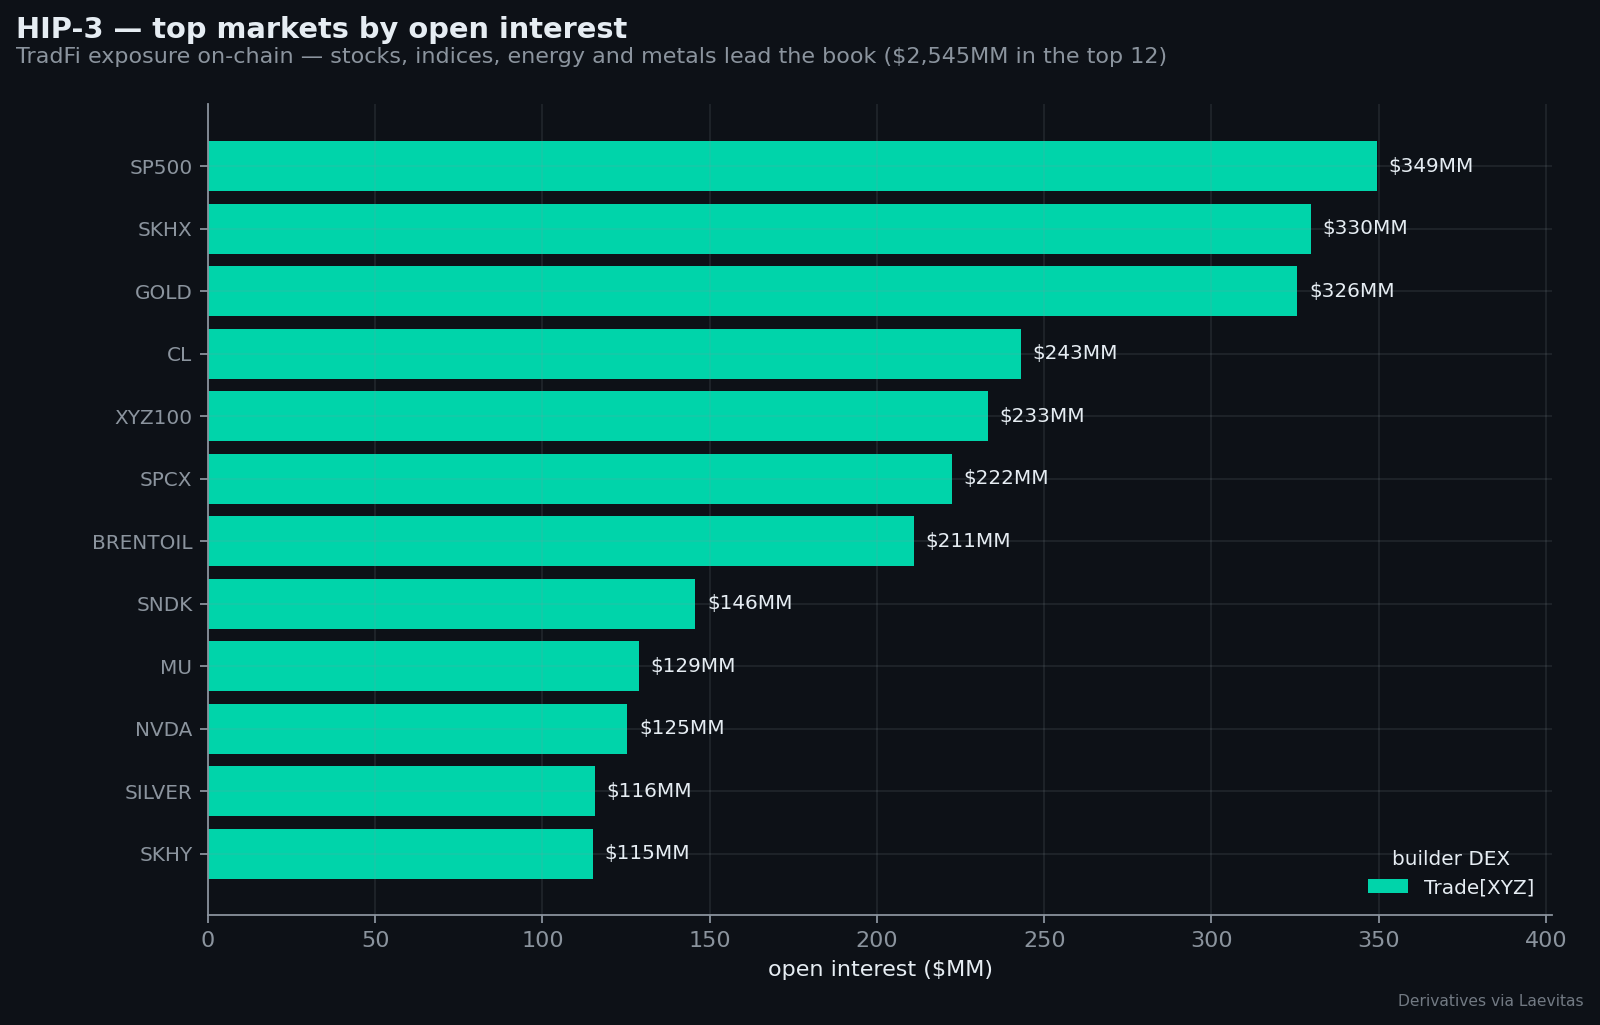
HIP-3 marketsThe @tradexyz book holds $2,545MM across its top 12 markets, led by xyz:SP500 at $349MM, xyz:SKHX at $330MM and xyz:GOLD at $326MM. Four memory names sit in that dozen, SKHX plus SNDK at $146MM, MU at $129MM and SKHY at $115MM, together $720MM of OI, which is more than twice the size of the S&P market.
Sign-offWhat the week leaves is a builder book carrying genuine cross-asset risk, $2,545MM of TradFi exposure in the top 12 @tradexyz markets alone, a crude complex whose shorts are still paying 50-64% annualised to hold and which is absent from the week’s top twelve liquidations altogether, and same-asset funding gaps of 90pp-plus that survive only because the secondary books are too thin to flatten them. Native HL, through all of it, stayed at its funding defaults. Midweek Hyperliquid | 2026-09-03 | Derivatives via Laevitas |
||
|
You are receiving this because you subscribed to the Crypto Derivatives Briefs at laevitas.ch. Laevitas SA, Switzerland. Unsubscribe · Privacy |