
The Monday Brief // 31Aug26
Rick @scopicview - Head of Markets, Laevitas
Jackson Hole passed without the dovish pivot some had positioned for; rates sold off across the curve into and around the speech and the long end stayed under pressure, a price action consistent with a reaffirmed 2% inflation commitment rather than any softening of tone. The regime carrying in is a fragile goldilocks - equities near records and cross-asset volatility close to its 2026 lows, coexisting with above-target inflation and a Fed still debating hikes rather than cuts. A weekend exchange of strikes between the US and Iran and fresh noise around US-China trade terms add a geopolitical layer to a week that culminates in Friday’s August payrolls.
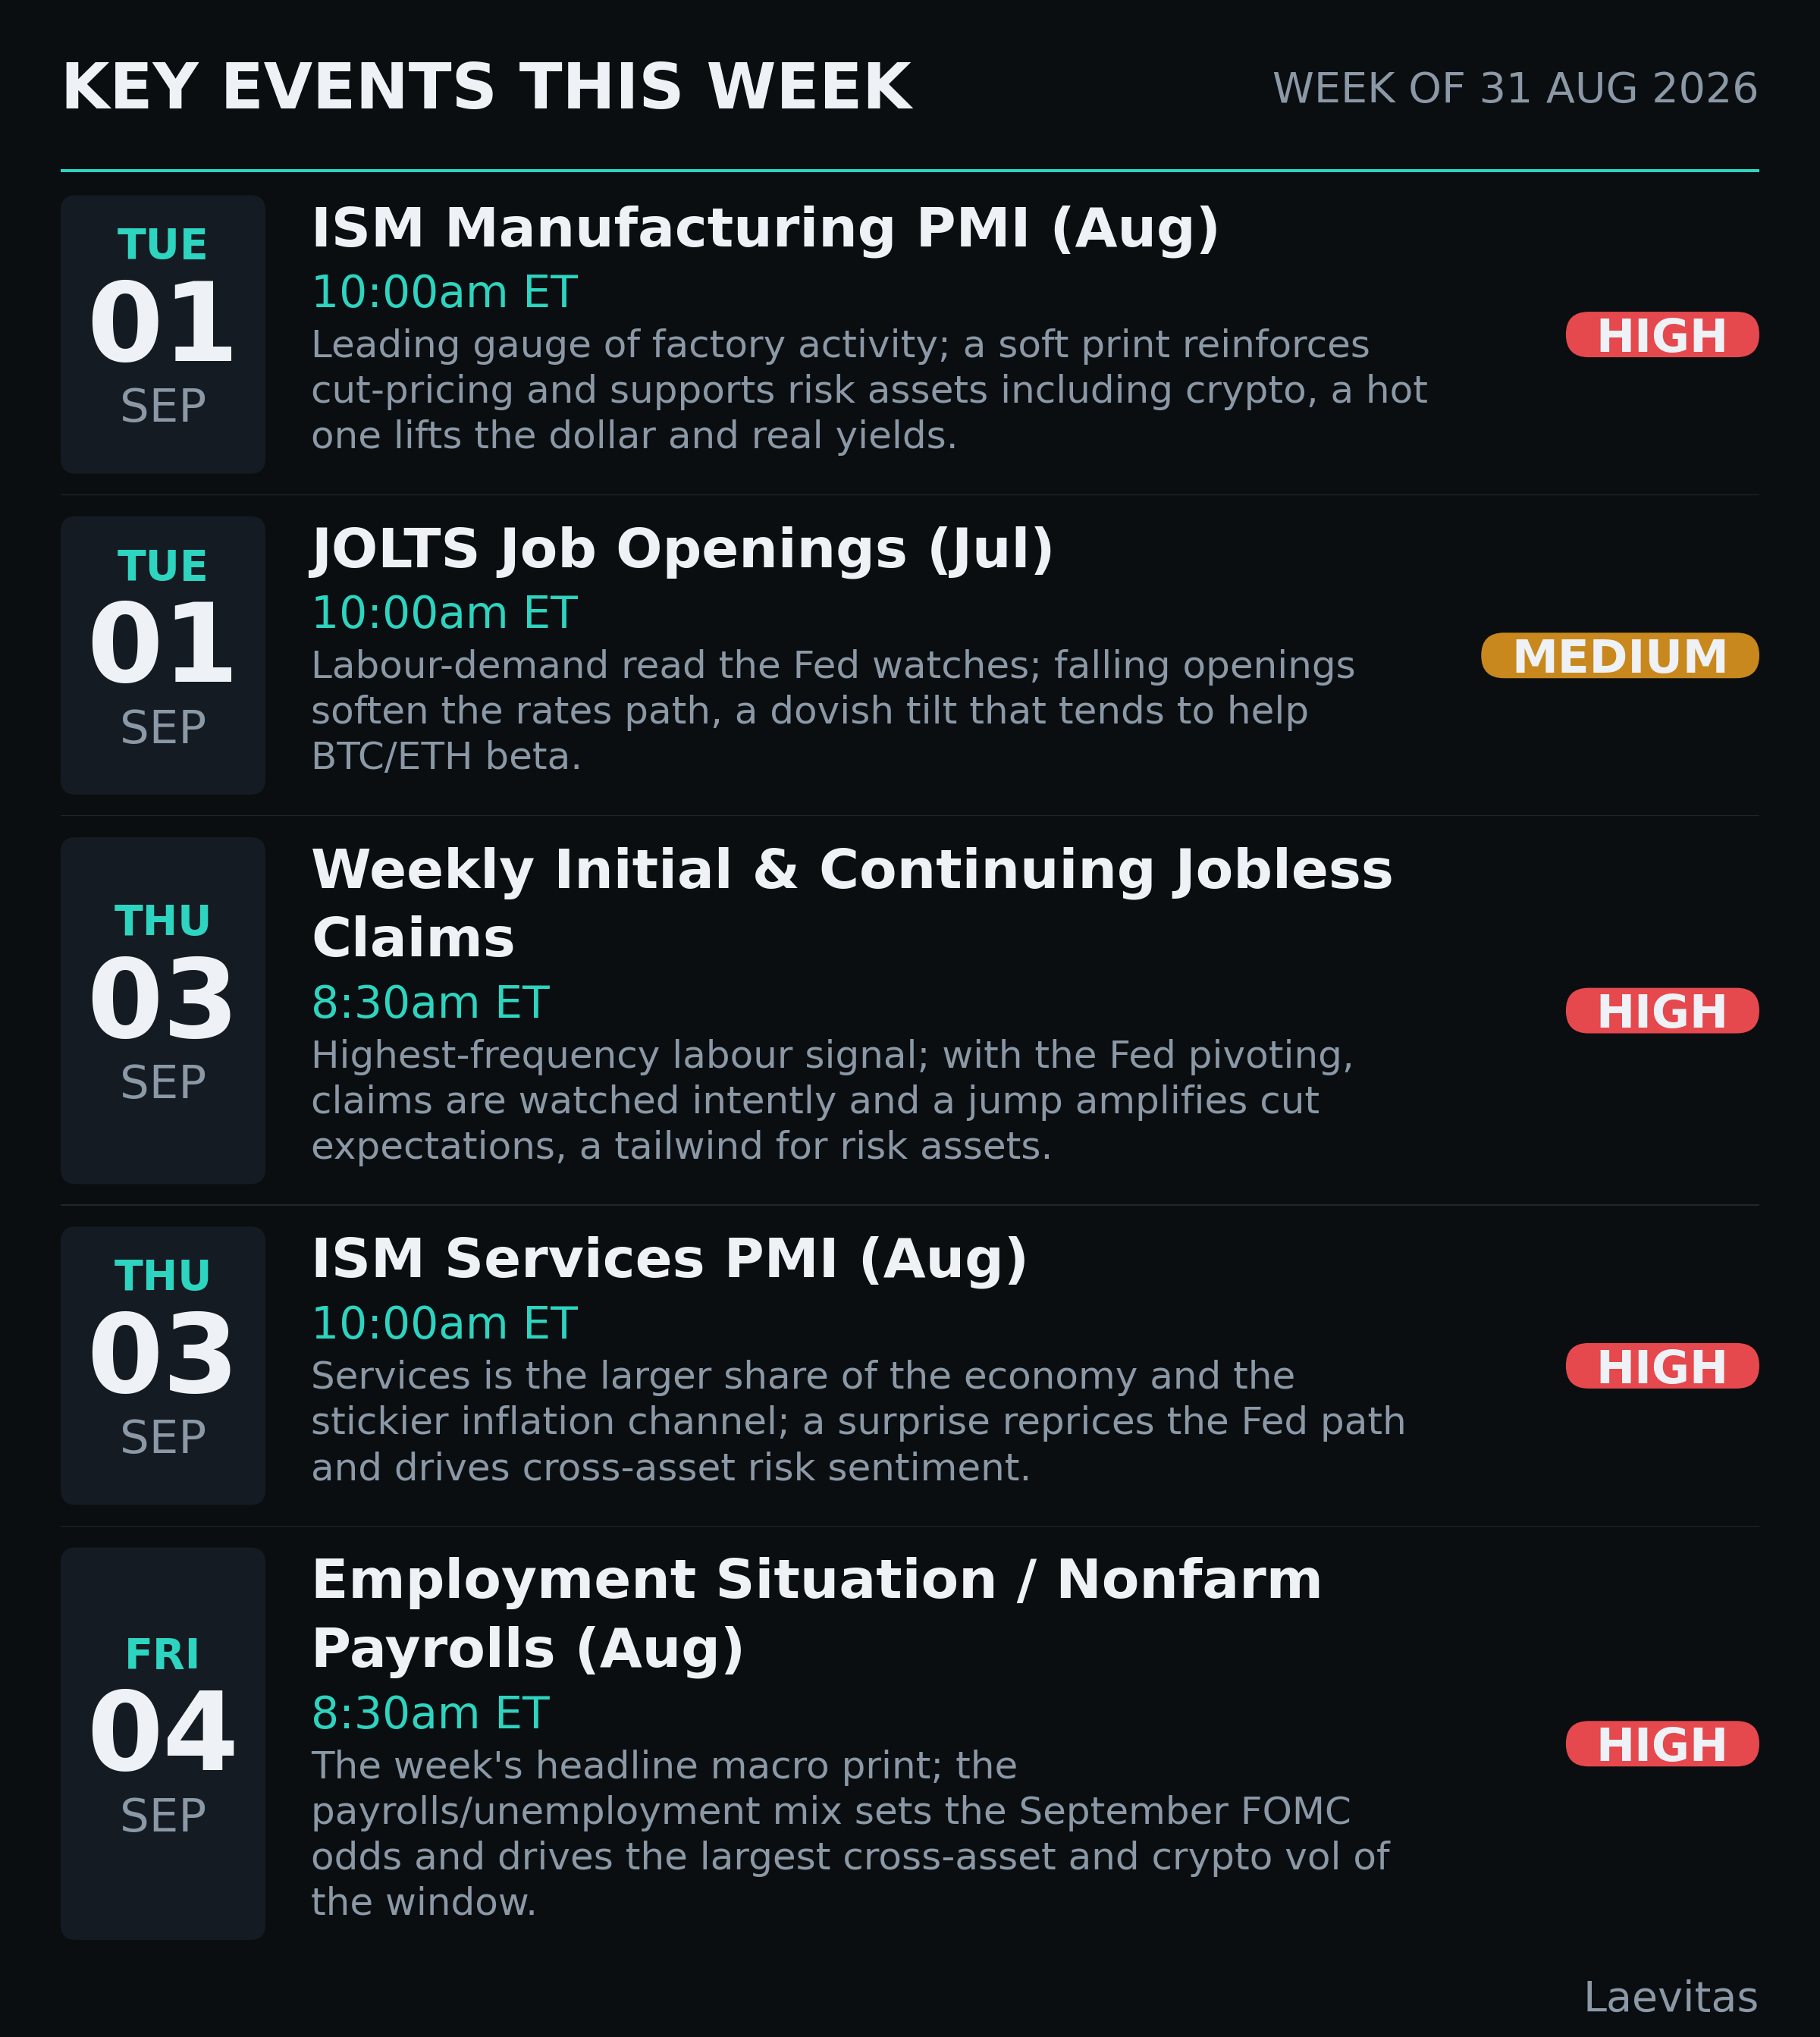
Key events this week
Macro
The cross-asset backdrop is unusually benign on the surface and structurally stretched underneath. US financial conditions sat at their most accommodative since 1996 through mid-August, equity indices are grinding to fresh records, and volatility gauges printed 2026 lows, yet headline and core inflation remain above target in both the US and the euro area. That combination is internally inconsistent: either robust growth and loose conditions force central banks to tighten more than is priced, or growth softens enough to undercut the risk-asset bid that the whole configuration rests on. The historical rhyme is early 2024, when priced cuts failed to arrive and the US 10y backed up from 3.88% to 4.70% while equities held; that 4.70% level is again the line in the sand for the long end, and a sustained break through it would be the clearest signal that the hawkish scenario is turning from theme into price.
The Fed itself is the pivot. The July minutes carried three dissents in favour of a hike, and the debate into September is whether to move again from 3.50-3.75%, not whether to ease; the OIS strip prices roughly a 30% chance of a September hike and a little over a full 25bp cumulatively by January. The direction of travel matters more than any single print: soft July jobs and CPI cooled hike odds through mid-August, then firmer late-August inflation reasserted the hawkish tilt and pushed term premia higher. The genuine disagreement worth holding is on the scale of what follows - one credible reading looks for as much as 75bp of further tightening into year-end, another for a hold clear through 2027, a gap wide enough that Friday’s payrolls becomes the single most important repricing catalyst of the quarter.
The long end is therefore the master gauge for crypto this cycle, and the pressures on it are fiscal and structural as much as cyclical - Treasury buyback interventions that bought only a brief rally, deficit supply, and term-premium rebuilding that still has room to run. Oil is the live cross-asset inflation channel: Brent fell roughly 9% in the last week of August, touching $86/bbl on hopes of an interim Hormuz shipping arrangement, but the weekend strikes reintroduce two-way risk to that path. The most underpriced tail sits in Japan, where the policy forecast has shifted to a September BoJ hike; a hawkish repricing of the yen would reprise the August 2024 carry-unwind template that drains global risk liquidity, and the dollar channel through all of this remains load-bearing for crypto given its inverse correlation to the currency.
Crypto
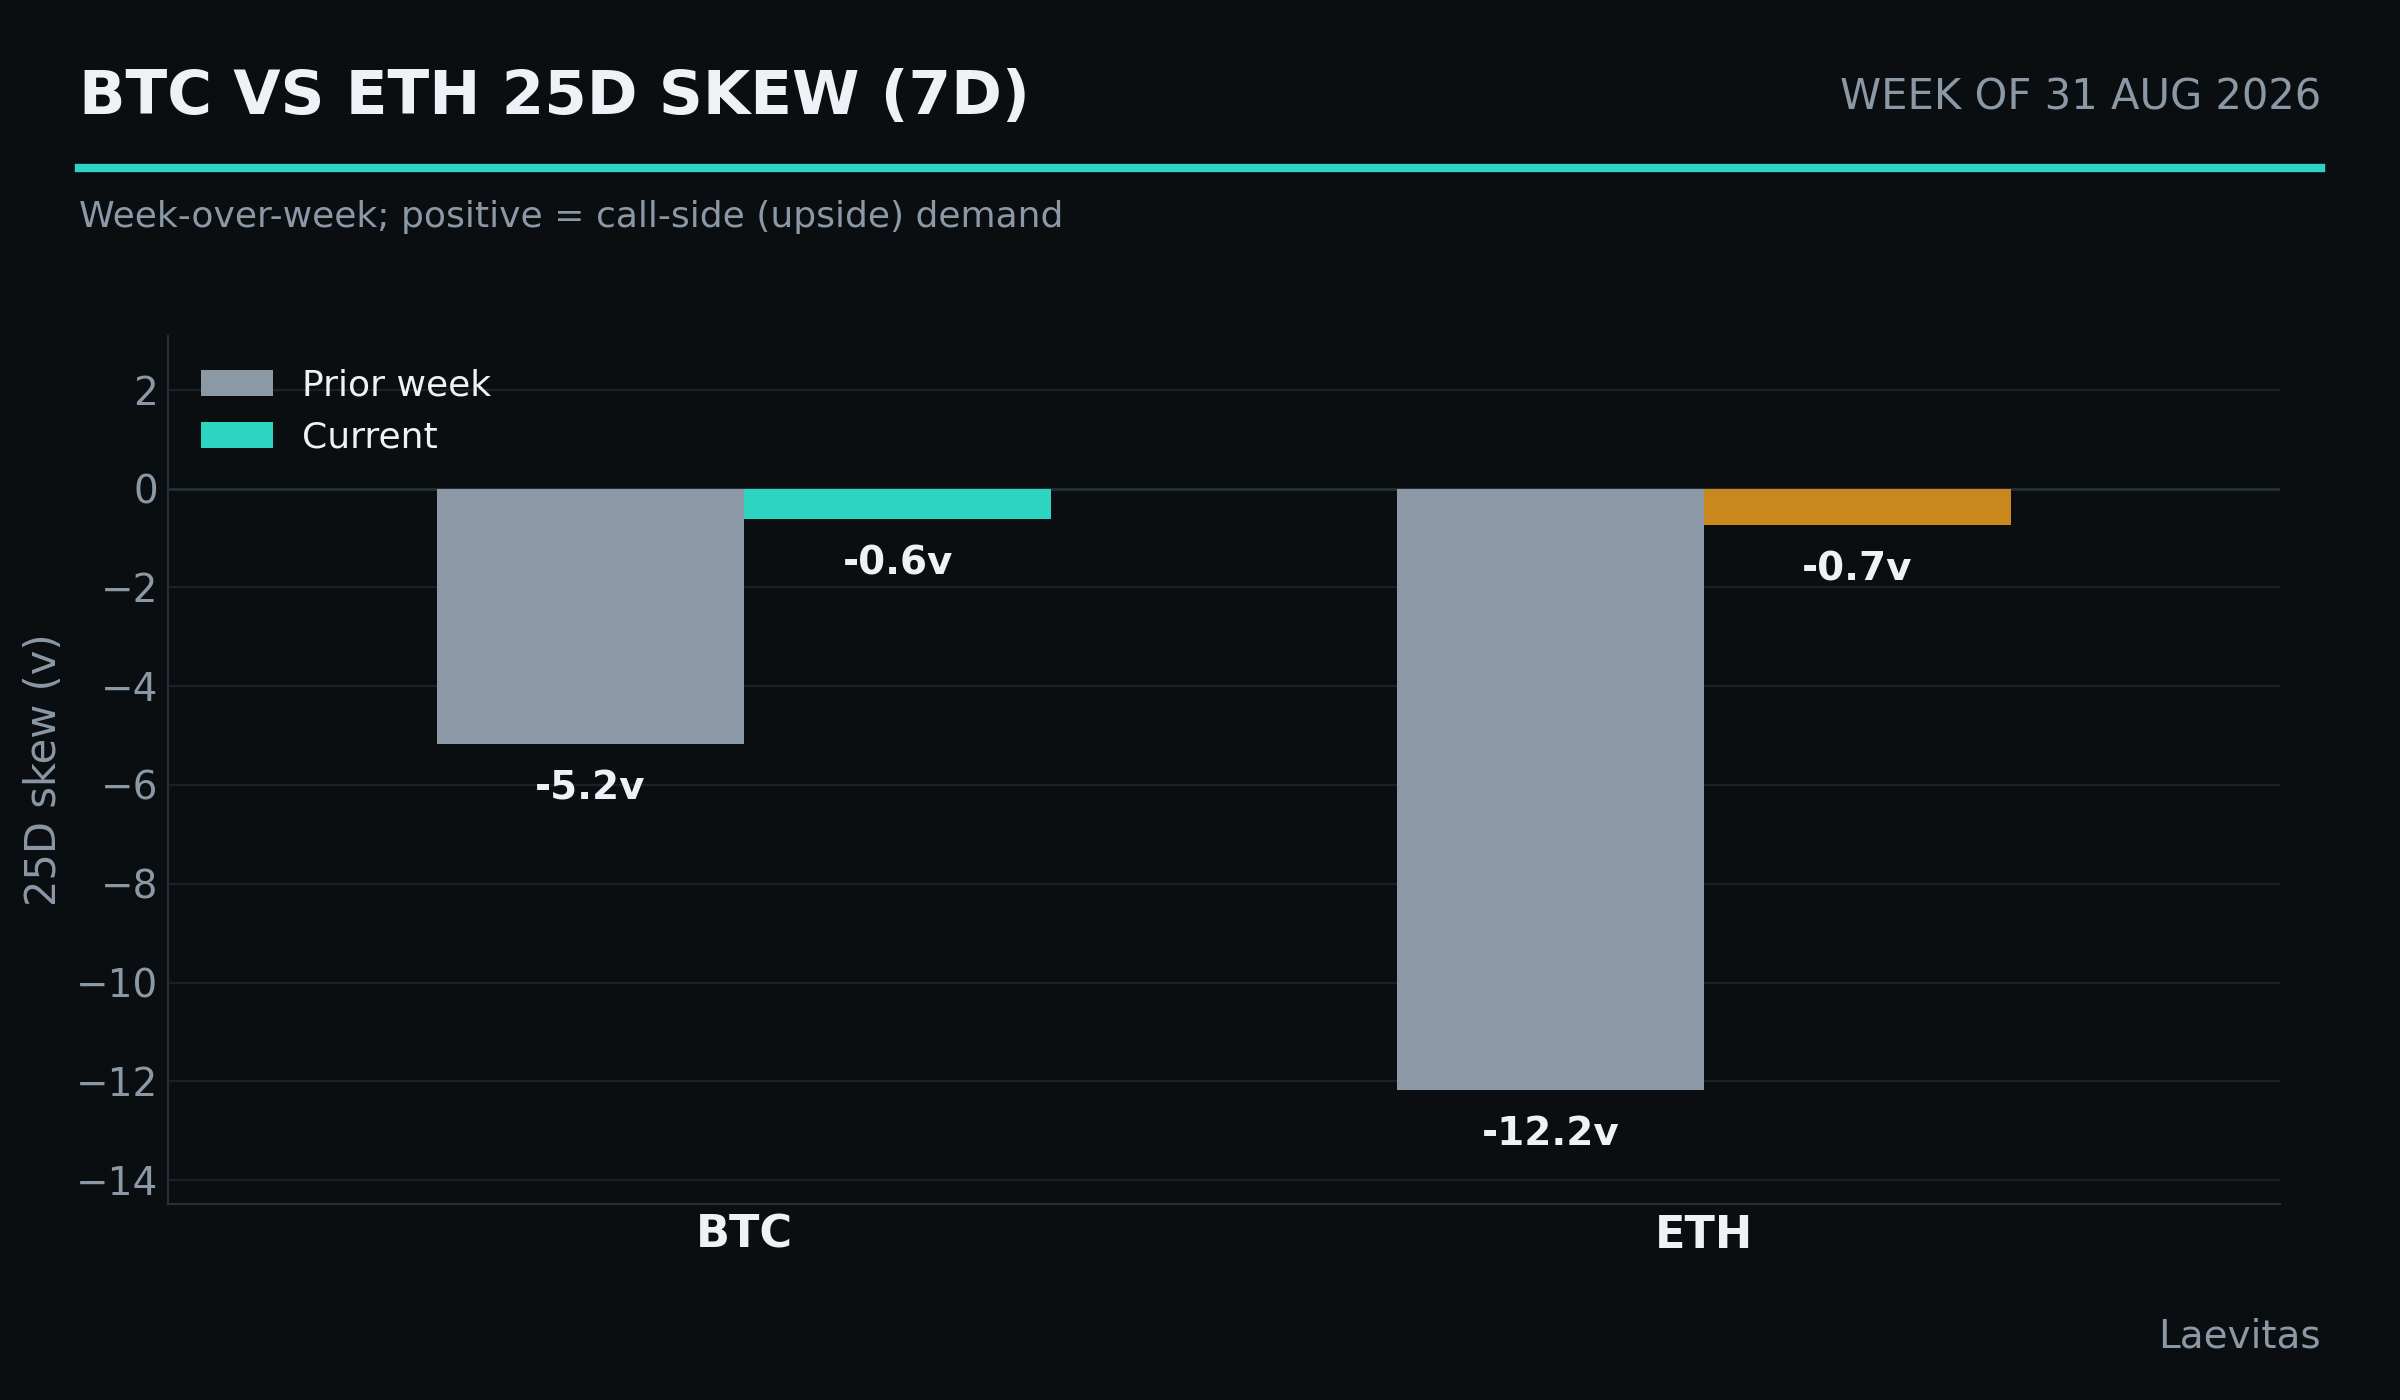
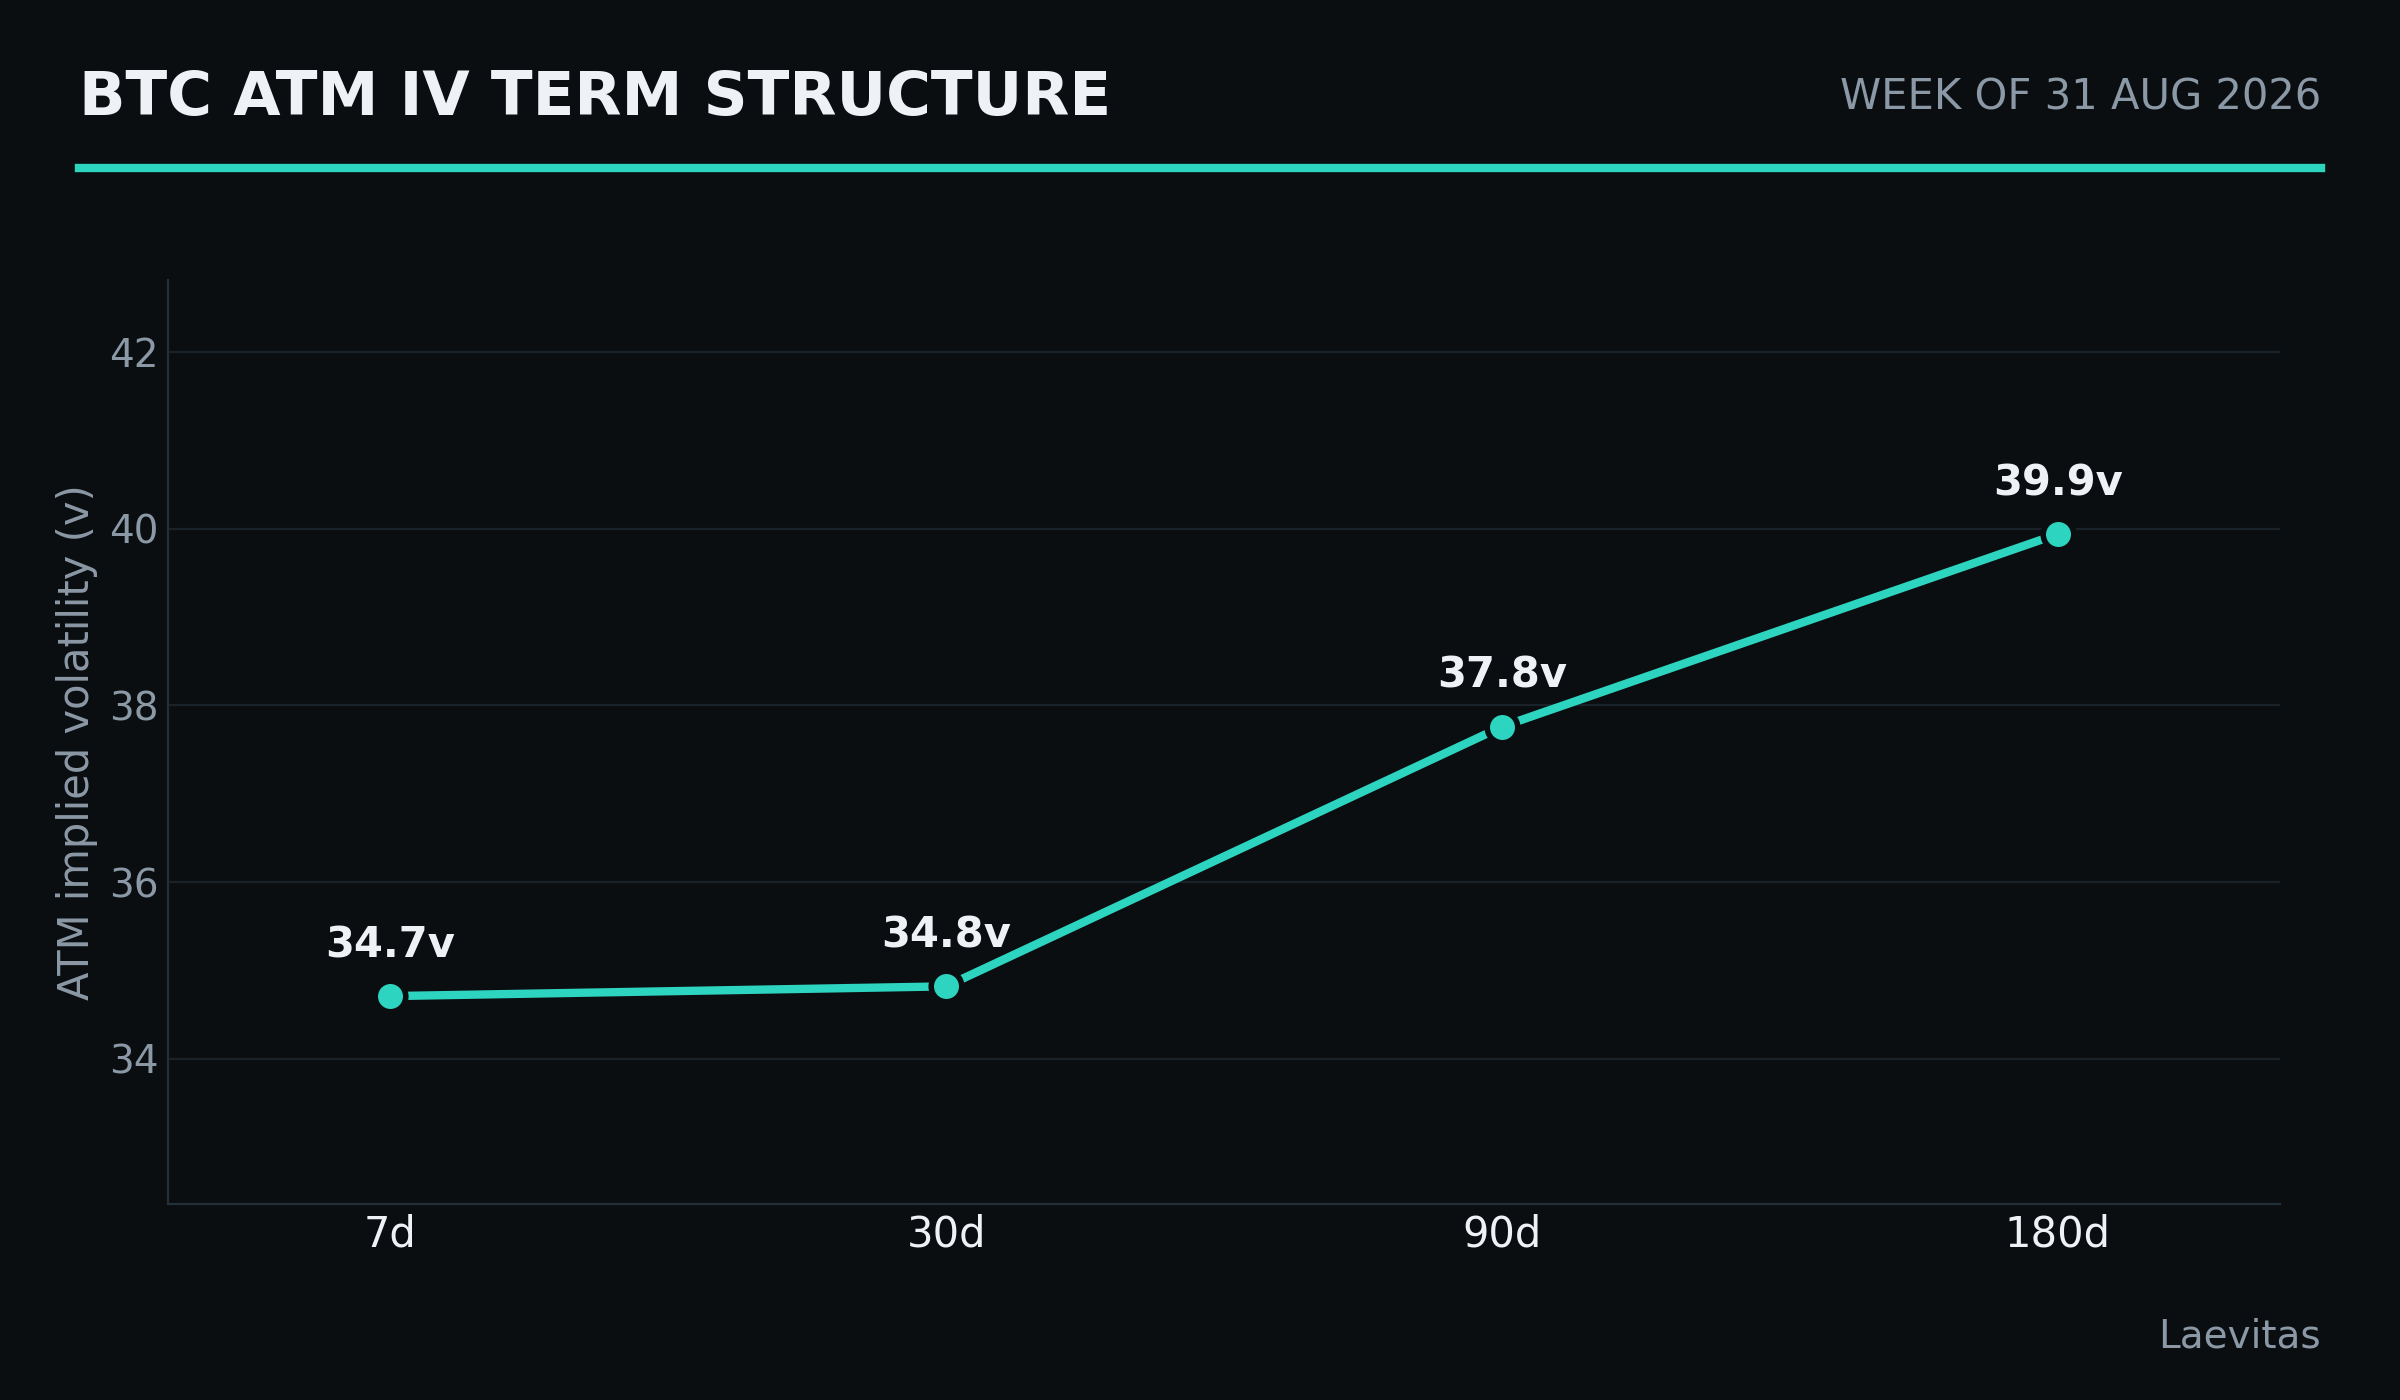
The dominant move on the surface is a violent normalisation off last week’s risk-off spike. 25D skew ripped from about -5.2v back to -0.6v on $BTC at the 7d tenor and from roughly -12.2v to -0.7v on $ETH in a week, unwinding almost the entire downside put bid that had defined the prior surface. Front-end ATM implied vol was crushed alongside it, $BTC 7d from 47.7v to 34.7v and $ETH 7d from 68.0v to 48.3v, and the term structure has re-steepened out of last week’s front-end inversion into a gentle upward slope - $BTC 34.7v at 7d rising through 37.8v at 90d to 39.9v at 180d, $ETH 48.3v building to 54.6v at 180d. The result is a calm, contango-shaped surface pricing little event risk into a data-heavy week.
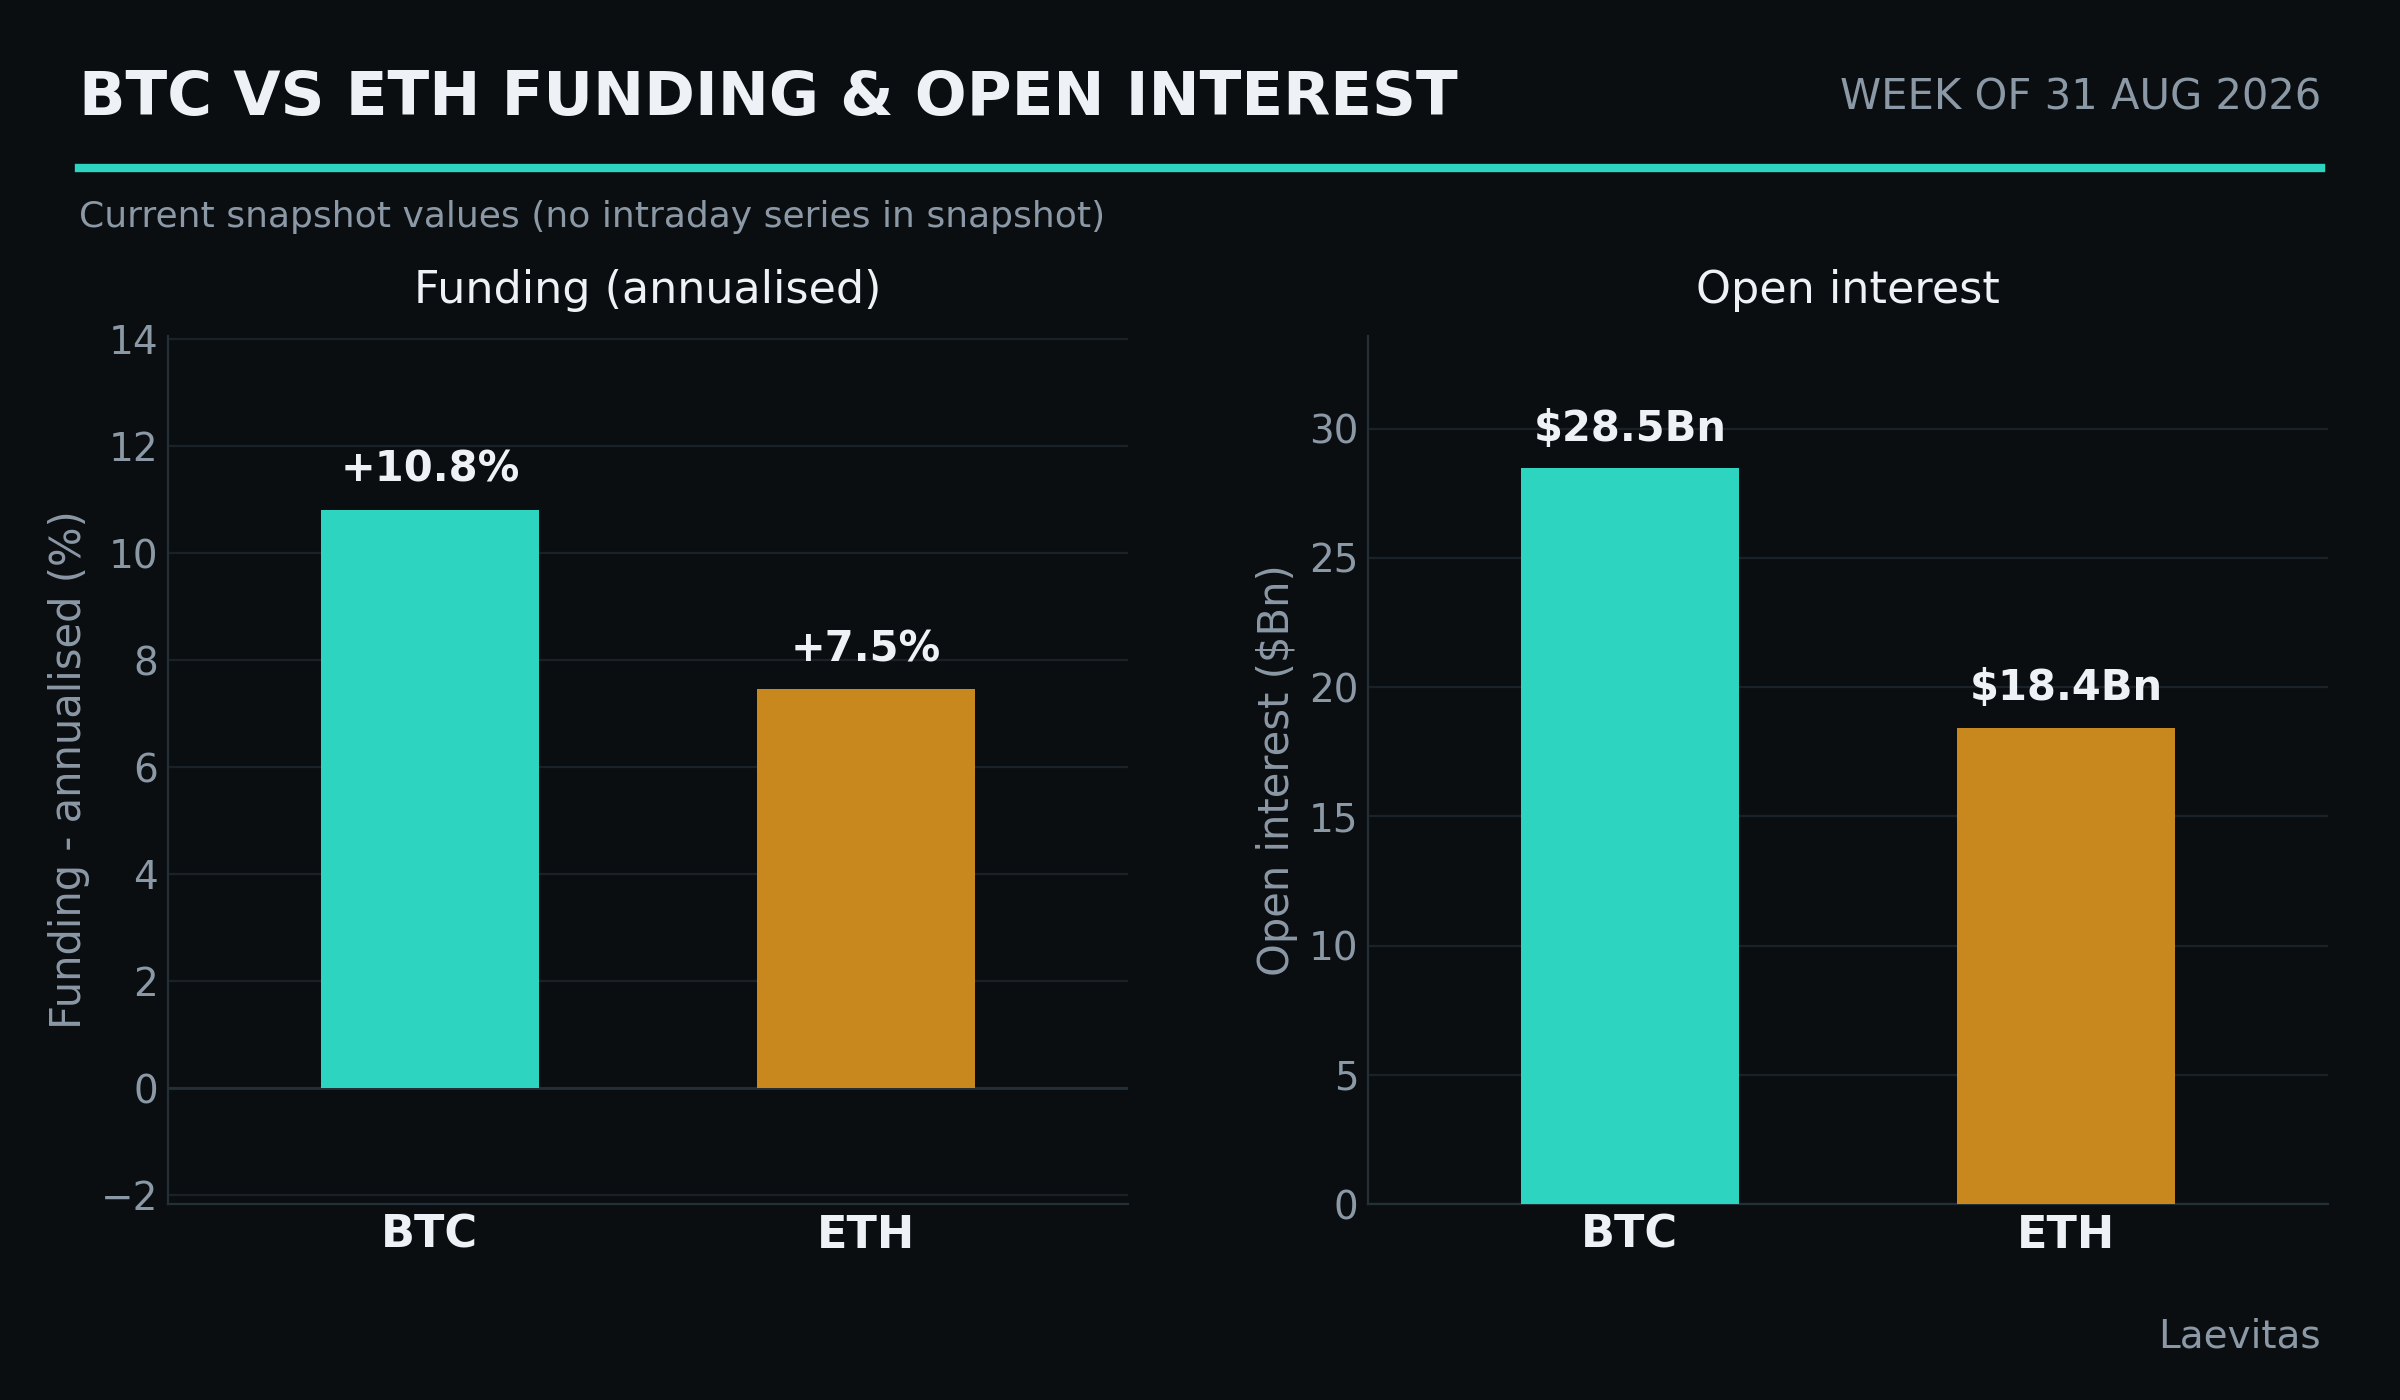
Realised is still doing the work under that calm. On the IV-RV construction $BTC 7d realised of 37.6v is running above 33.7v implied, so delivered movement is outpacing what the front of the curve charges for it; $ETH sits the other way, with 47.7v implied over 43.7v realised. Funding is modest and positive - $BTC at 10.8% annualised, flat on the week, against $ETH easing to 7.5% from 9.0% - while open interest holds at $28,460MM on $BTC and $18,413MM on $ETH, and the long/short split diverges, $BTC at 0.63 leaning net short against $ETH at 1.29 leaning net long. With ATM vol compressed to these levels and skew back toward flat, front-end optionality screens cheap into a payrolls print and a live FOMC that between them can move the whole macro grid.
The market has fully priced the relief - skew normalised, vol crushed, the surface reset to a placid goldilocks configuration - at precisely the moment the macro backdrop turns more two-sided, with firmer inflation, a live September FOMC, payrolls on Friday, and a BoJ now leaning toward a hike. That compression leaves little cushion, and a hawkish payrolls surprise or an oil spike out of the Hormuz flashpoint would land on a surface charging almost nothing for it. The tension for the week is whether cheap front-end volatility reflects a genuinely quiet data-flow or a mispricing of a binary calendar; the direction of travel, soft data giving way to firmer inflation, argues that the risk is skewed to a hawkish shock the surface is not paid to carry.
Positioning into the week
- Cheap downside convexity in $BTC and $ETH: with 7d ATM implied vol crushed to 34.7v on $BTC and 48.3v on $ETH and skew reset toward flat, front-end optionality screens cheap into a payrolls-and-FOMC window whose risks skew two-sided.
- Skew normalisation as the risk-appetite read: the snap in 25D skew from -5.2v to -0.6v on $BTC and from -12.2v to -0.7v on $ETH marks the unwind of last week’s put bid, and a renewed slide back negative would flag the risk-off impulse returning.
- The long end as the master macro gauge: a US 10y yield pressing toward 4.70% would confirm the hawkish repricing that historically drains liquidity from long-duration risk assets, crypto included.
- Positioning divergence between the majors: $BTC funding at 10.8% annualised with a 0.63 long/short ratio sits against $ETH at 7.5% and 1.29, a split that leaves $ETH longs the more exposed to a downside catalyst.
- BoJ carry as the standing tail: with a September BoJ hike now the base case, a hawkish yen repricing would reprise the August 2024 carry-unwind template that compresses global risk liquidity.
Week ahead | 2026-08-31 | Derivatives via Laevitas