
The Monday Brief // 12Oct26
Rick @scopicview - Head of Markets, Laevitas
Last week’s pivot resolved hawkishly: the September FOMC minutes, released on Wednesday, confirmed a unanimous vote for the September hike and a majority leaning towards one more move before year-end. Brent round-tripped around it, trading above $105/bbl on Thursday on reports that the US could resume major combat operations in Iran before the midterms, then settling back at $103/bbl on Friday once the no-strike-before-the-midterms line came through. That leaves the October meeting close to priced out, December priced around 85% for a hike, and a single September CPI print on Wednesday as the one release with the standing to reopen the question.
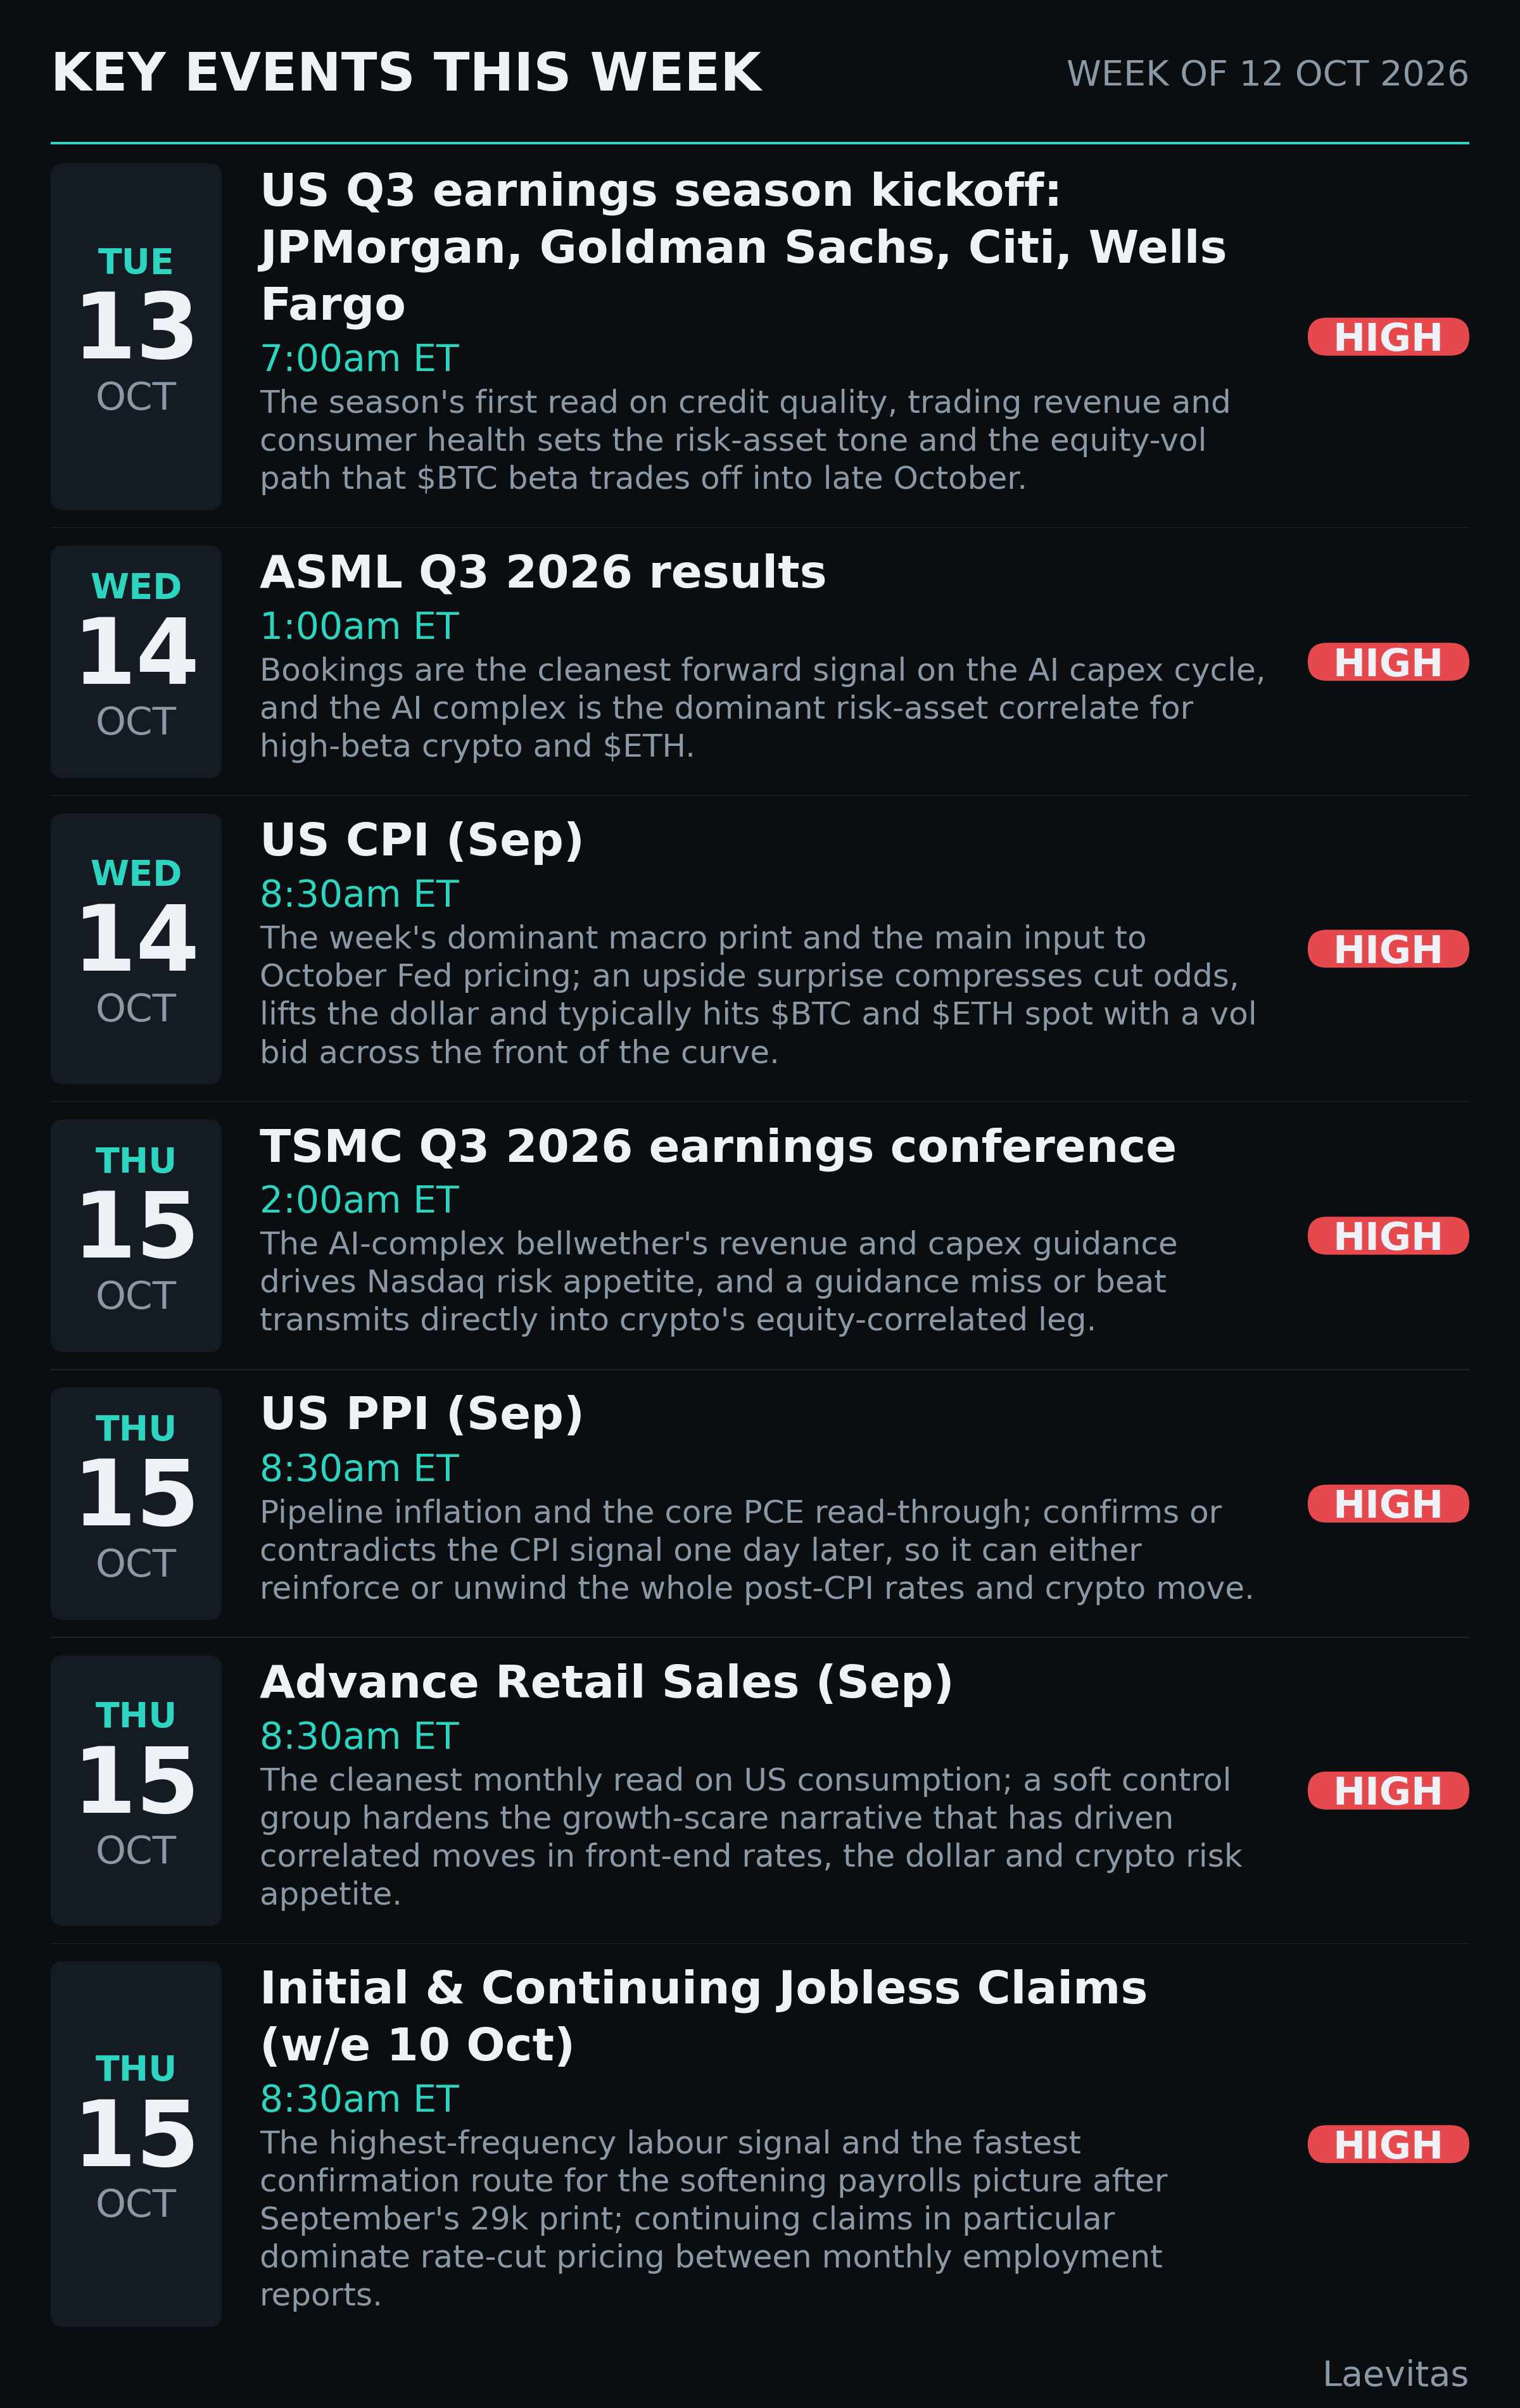
Key events this week
Macro
Policy still runs in one direction, and the week’s communications gave no reason to think otherwise. Governor Waller’s framing on Thursday - that further hikes will likely be needed to slow inflation, though consecutive meetings are unnecessary and the pace depends on incoming data - is the cleanest statement of how October gets skipped without the cycle being declared finished. The tightening is also synchronous; the RBA has hiked to 4.6%, BoJ officials flagged broadening inflationary pressures at their October branch managers’ meeting, and the policy bias across emerging Asia has tilted hawkish against a firmer Fed. Any crypto thesis that needs an easing-driven liquidity impulse to work has nothing in the week’s data to lean on, and dollar cash yields remain a live competitor to perp carry, which compresses the fair value of funding and basis before positioning is even considered.
Where the pressure now sits has shifted, and that matters more for long-duration assets than the front-end debate does. The sell-off has transitioned from a bear flattener into a bear steepener, with the front end constrained at roughly 100bps of priced hikes while the long end reprices term premium on a fiscal outlook that has not improved, persistent supply and a diminishing pool of incremental buyers. The 30y breached 5.595%, its highest yield since 2002, having put on 25bps in the week to 30 September at a 4.4 standard-deviation move, and the 10y has traded at 5%. Europe supplies the same mechanism in sovereign form: 10y OAT-Bund retraced back to 140bps on Wednesday after a 13bp widening on comments that France’s bond market does not yet warrant intervention, before both OAT-Bund and BTP-Bund tightened 4bps on Friday; the 10y Italy-Germany spread was the single largest non-rates mover in the G4 screen at 7.2 standard deviations. A discount rate rising on fiscal risk without a growth offset is a harder environment for a non-yielding asset than a policy-led flattening would be.
Gold has already demonstrated what that regime does to a store-of-value thesis, falling 3.05% in the week to 30 September and a further 3.68% in the week to 2 October while USD 10y real yields rose 18bps at 2.8 standard deviations and the USD TWI gained 0.86%, against a EUR TWI down 0.86% at 2.8 standard deviations. $BTC was the second-best performing asset of Q3'26 behind oil on a thesis that overlaps substantially with gold’s, and gold’s liquid version of that thesis broke in September. The equity tape that crypto’s beta actually tracks is narrow rather than broad: NDX added 3.25% in the week to 25 September while R2K lost 0.68%, index breadth has plunged, and AI infrastructure accounts for roughly half of S&P EPS growth, which makes drawdown risk event-shaped. Equity inflows of $372bn in Q3 and the October-November buyback seasonal are genuine supports underneath all of this, and the week tests the narrow leg directly, with the large US banks opening third-quarter earnings on Tuesday and ASML and TSMC reporting mid-week.
Crypto
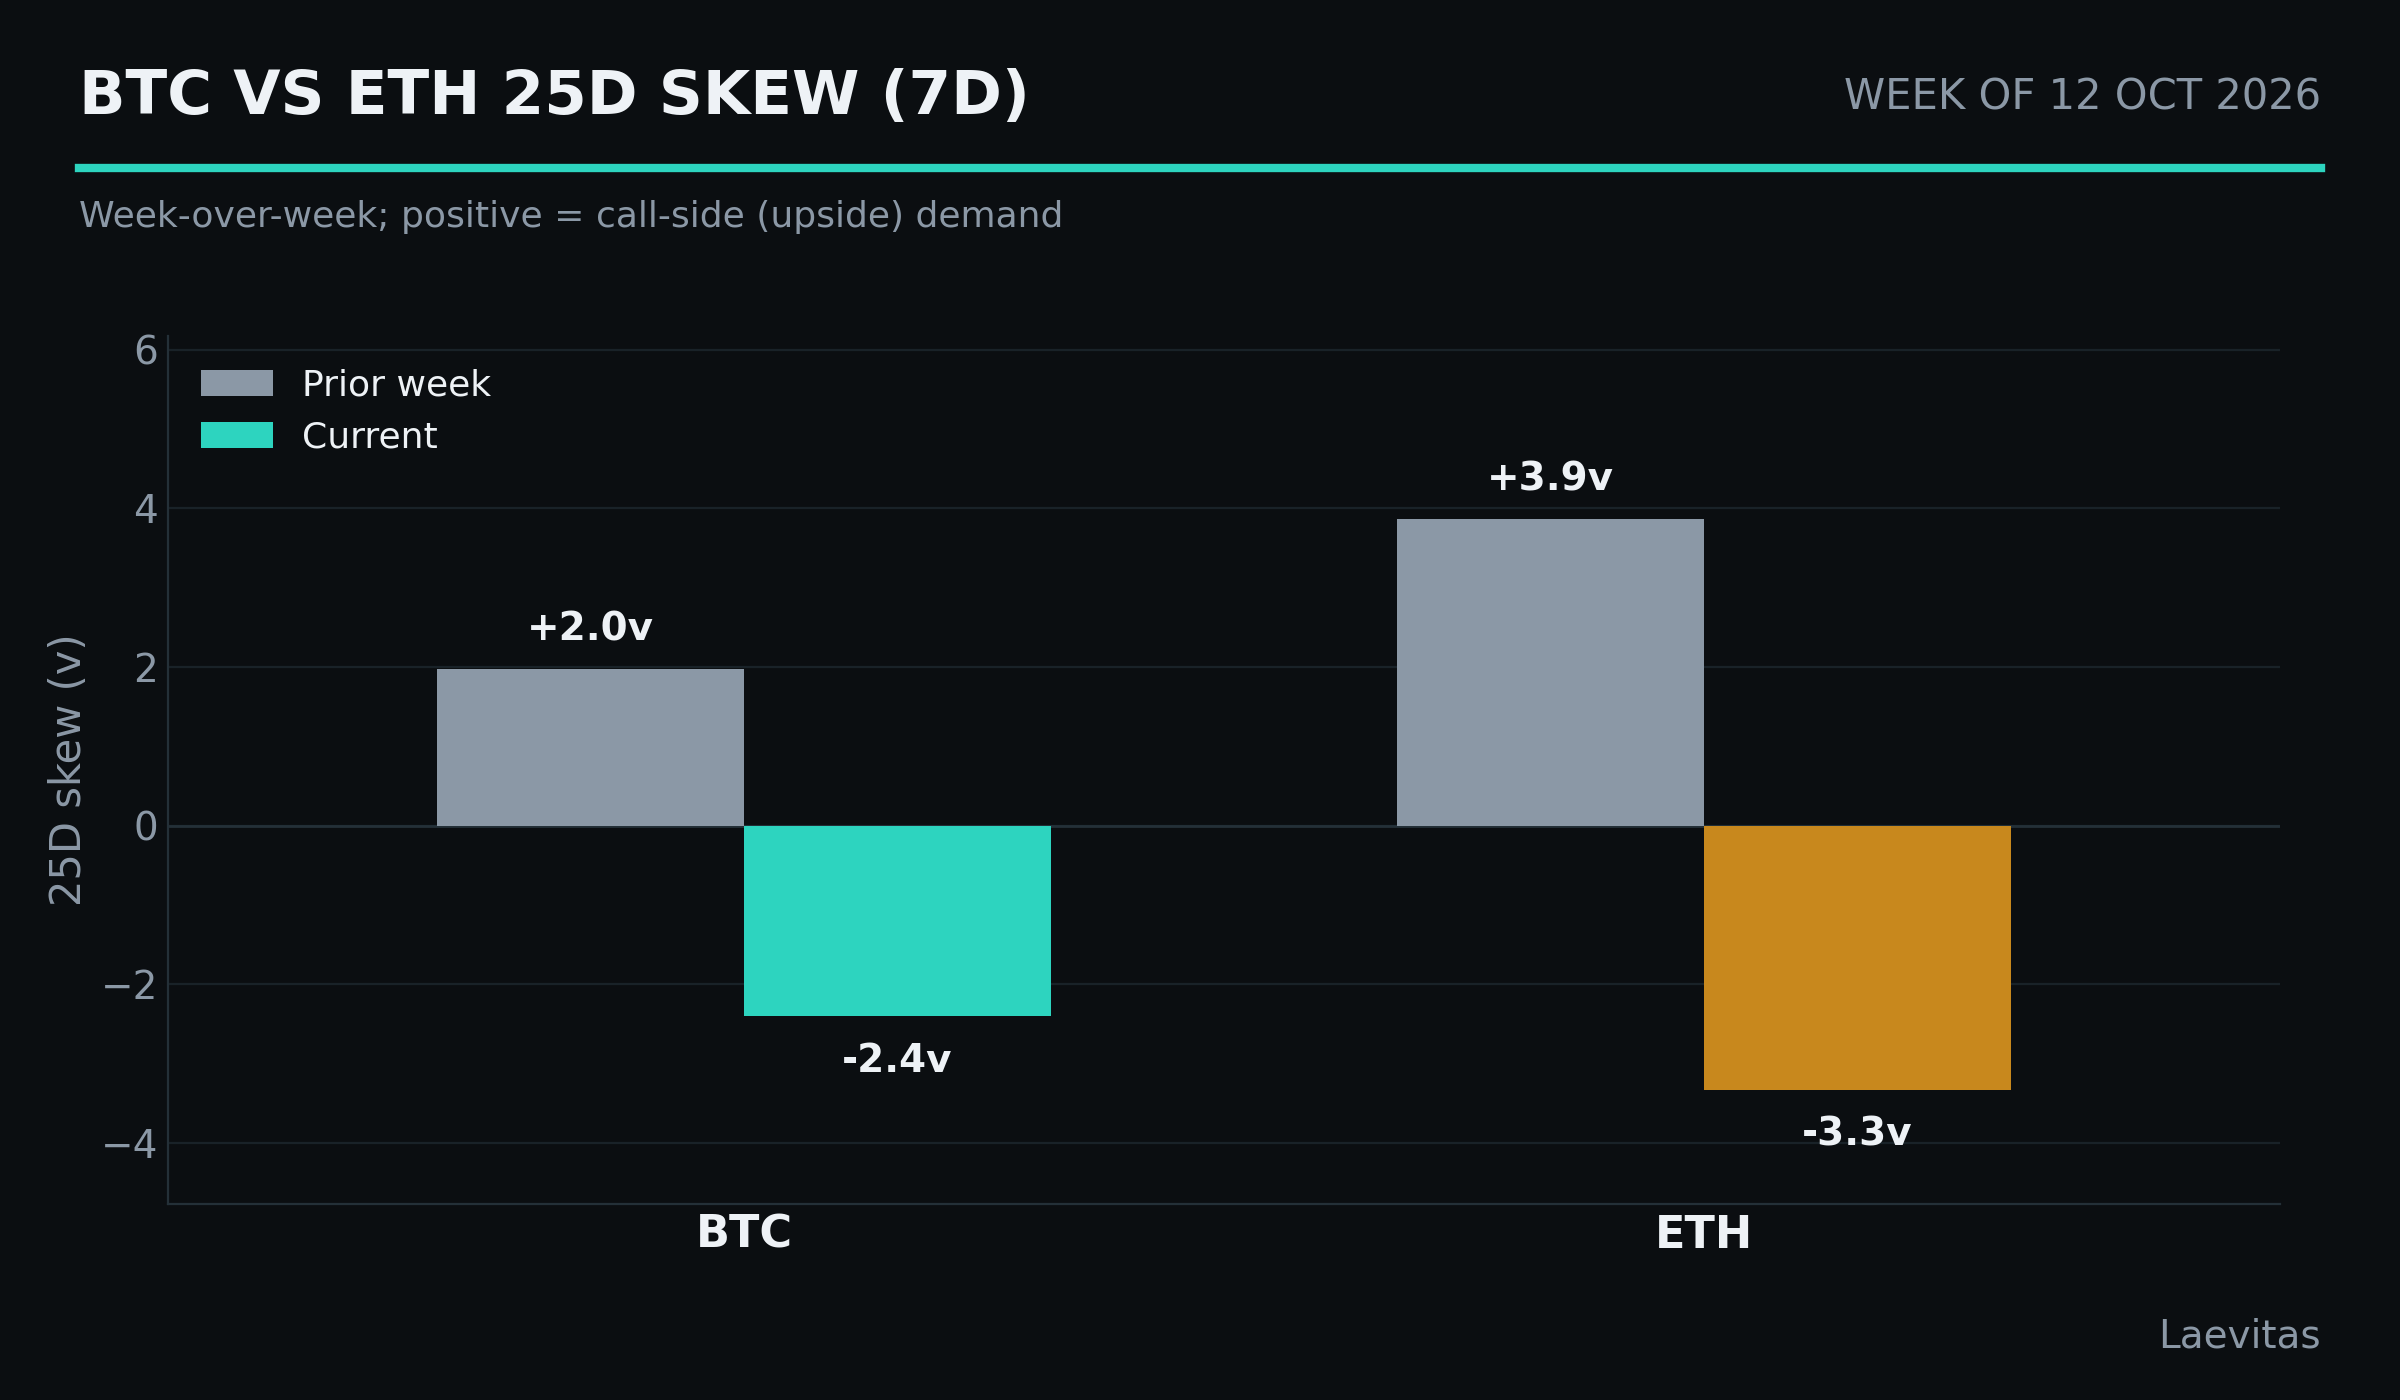
Skew did most of the work on the surface this week, round-tripping at the front end. $BTC 25D 7d skew swung from +1.98v to -2.40v, a 4.38v move in a week, and $ETH 7d went from +3.87v to -3.33v for a 7.20v move; the 30d legs followed more modestly, $BTC from -0.80v to -2.22v and $ETH from -0.05v to -1.92v. Both front ends are now nominally put-bid, and the distribution context is what gives the move its meaning: $BTC 7d sits at the 76th percentile of its 52-week range against a median of -4.40v, and $ETH 7d at the 57th percentile against a median of -3.88v, so puts remain cheaper relative to calls than they have been through most of the past year. This is the unwind of a call-bid extreme reaching only partway back towards normal, and at the 30d tenor, where $BTC holds the 82nd percentile and $ETH the 78th against medians of -4.66v and -3.64v, downside protection is still being offered at levels a genuine hedging bid would have taken out.
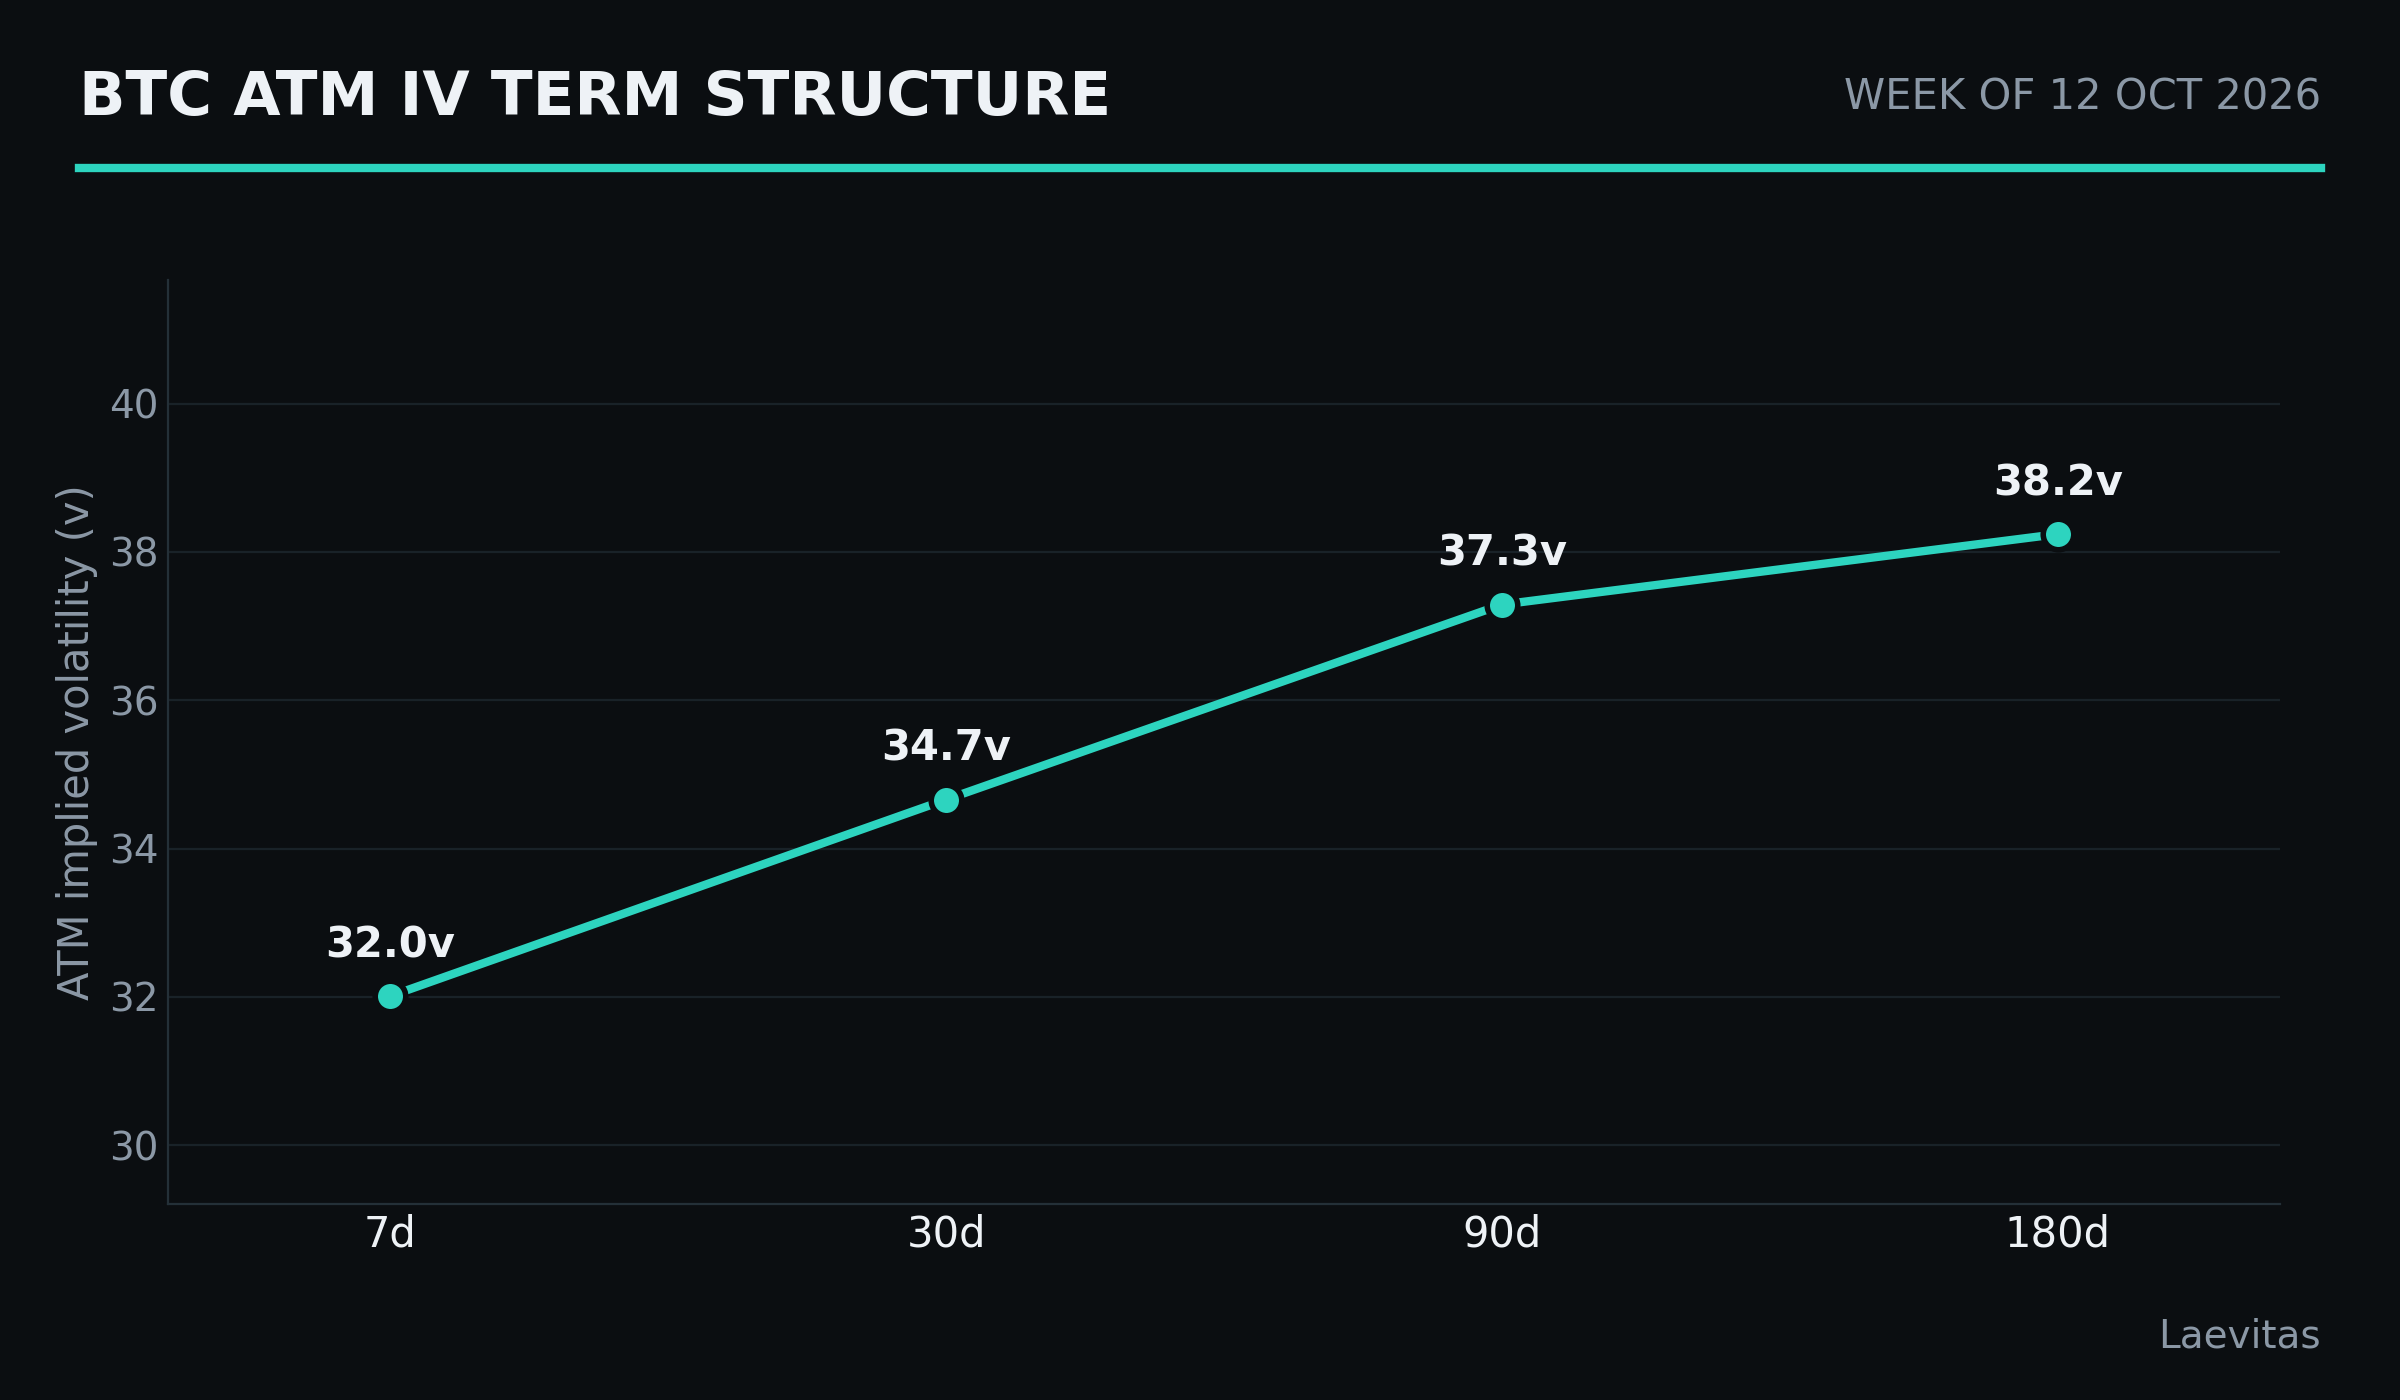
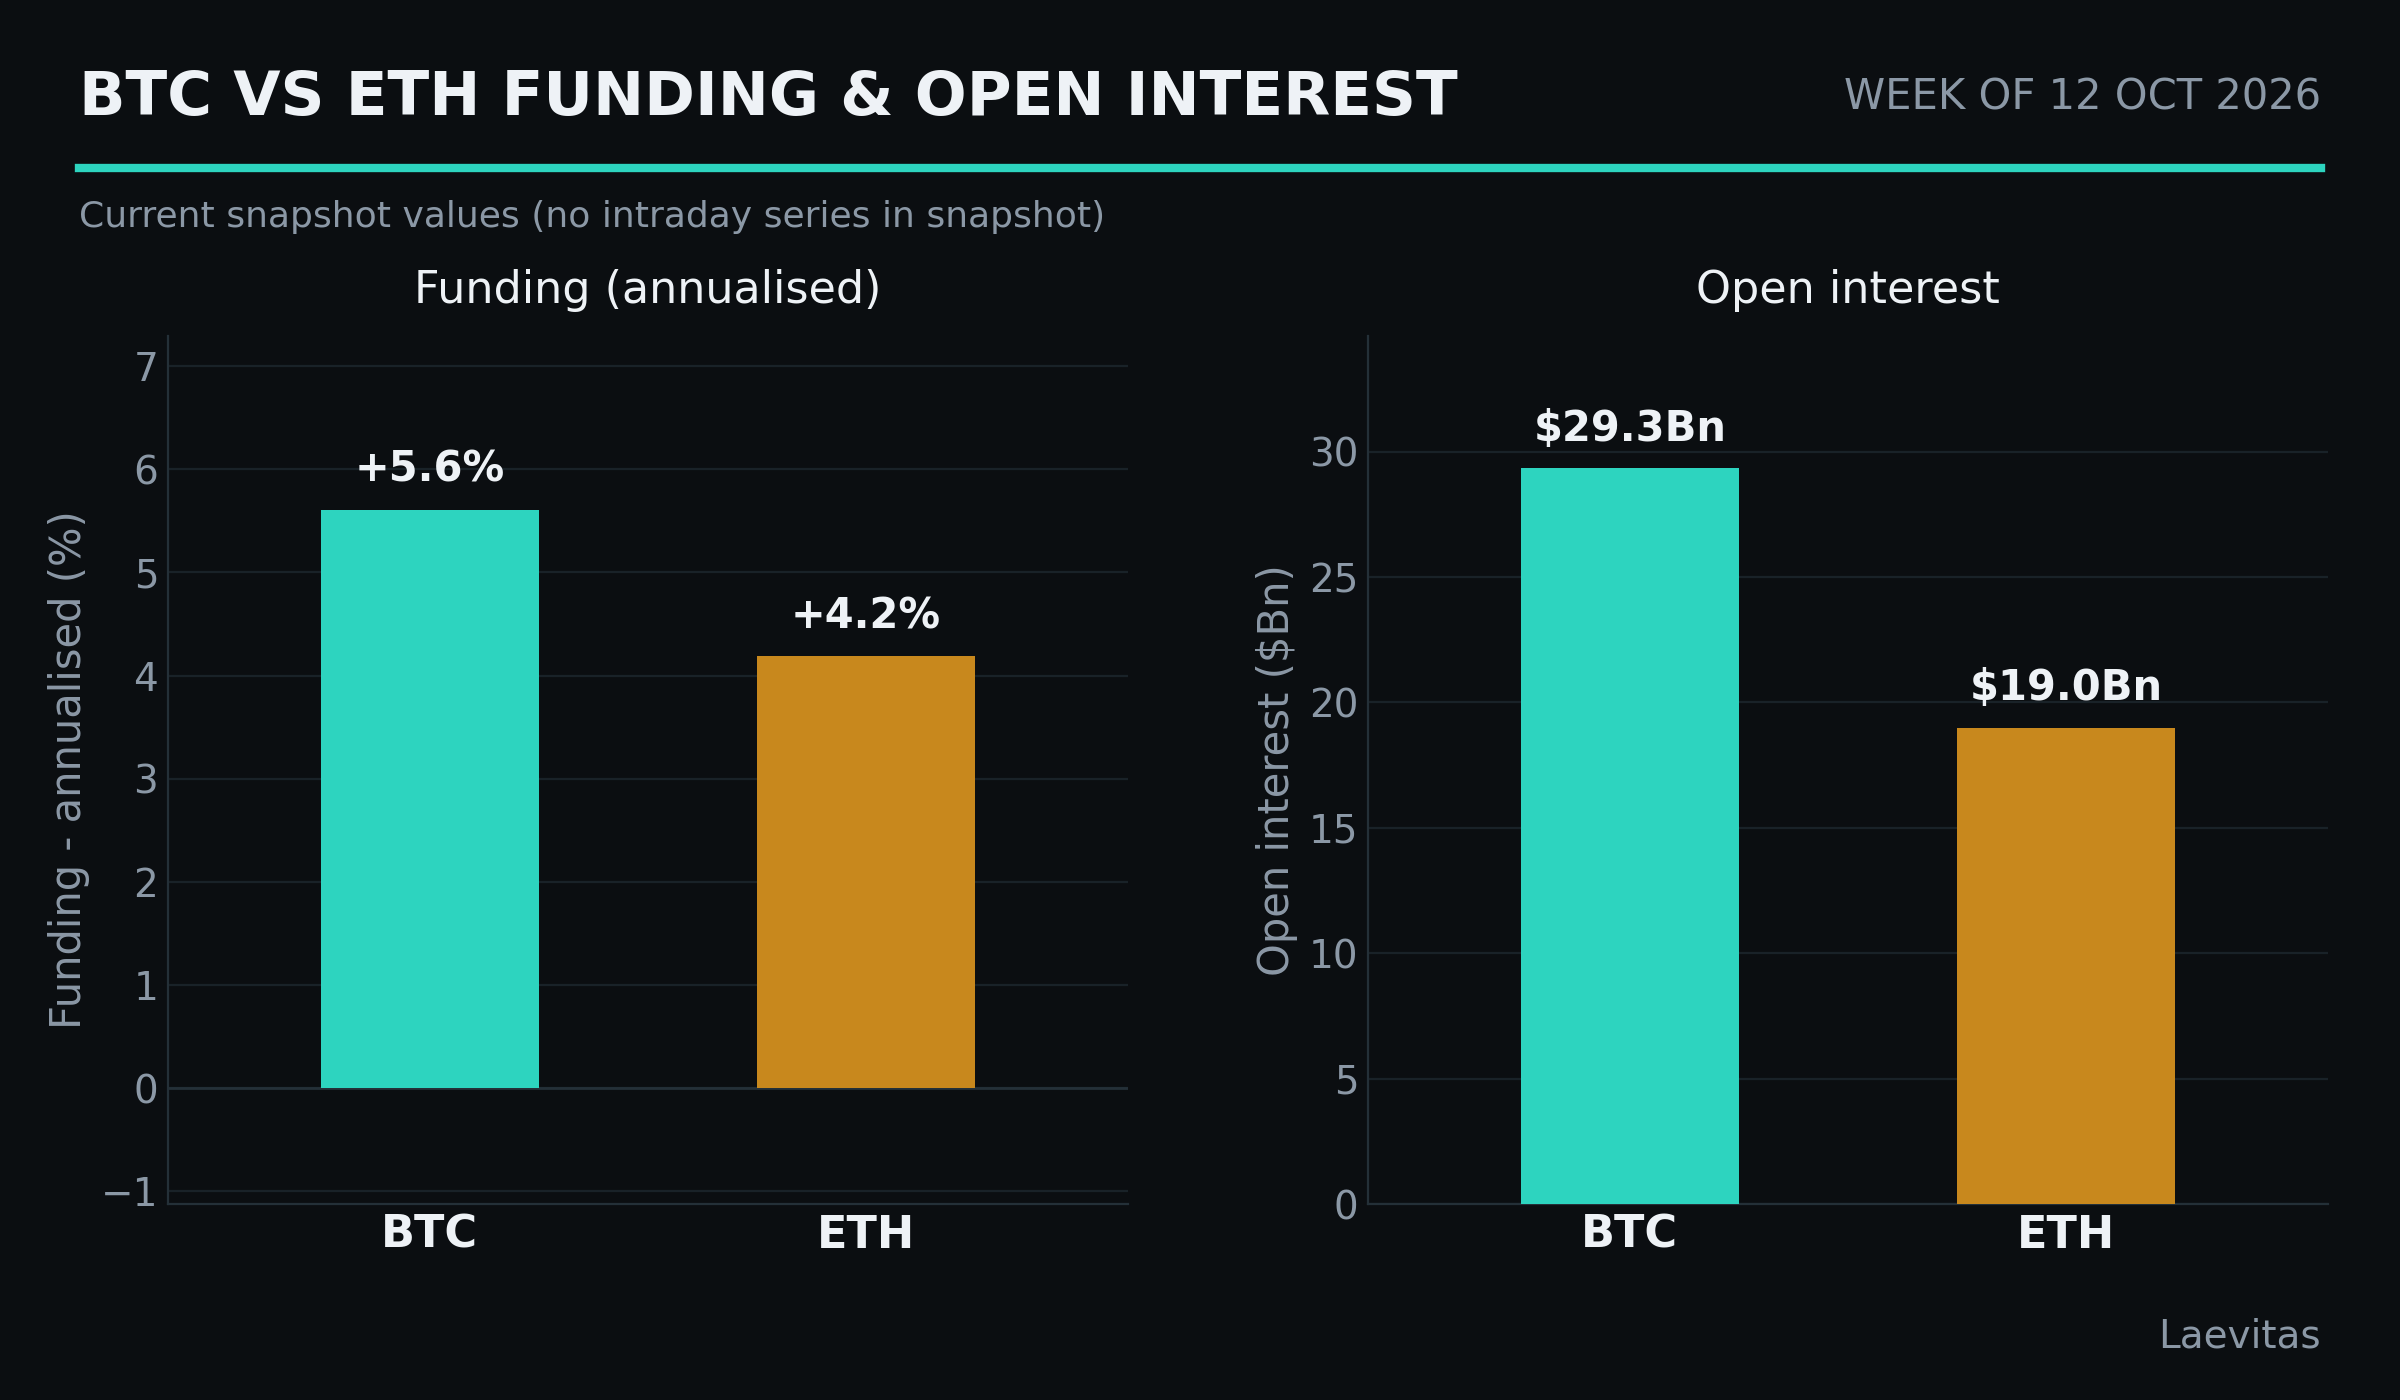
Term structure is upward sloping throughout and the front end is the cheap point. $BTC term-structure ATM IV runs 32.01v at 7d, 34.66v at 30d, 37.29v at 90d and 38.24v at 180d, with the 7d having come in from 34.5v a week ago; $ETH runs 41.67v, 46.38v, 50.37v and 52.60v across the same tenors, down from 43.6v at the front. A curve in that shape prices Wednesday’s CPI as a non-event. On the IV-RV construction, $BTC 7d implied of 32.2v carries 1.7v over 30.5v realised and the 30d 34.3v carries 2.2v over 32.1v, while $ETH 7d implied has converged onto delivered vol at 41.5v against 41.9v realised even as its 30d implied of 46.6v holds a 7.1v premium to 39.5v realised. Leverage is leaving alongside the vol compression: $BTC funding sits at 5.6% annualised with open interest down 1.9% on the week to $29,333MM, and $ETH funding has fallen from 6.0% to 4.2% with open interest off 6.9% to $18,999MM, with long/short ratios of 0.88 on $BTC against 1.52 on $ETH showing the positioning imbalance concentrated in $ETH.
The awkward configuration is a surface pricing a quiet front end into the single release capable of reopening the October meeting, with 7d $BTC ATM IV at 32.01v below every longer tenor and skew having unwound a call-bid extreme without reaching its own median. Direction from here turns on two variables the surface treats as settled, since a September CPI print hot enough to drag October back towards 50/50 would reprice the whole curve, while the Hormuz tape remains genuinely two-way and a de-escalation that restores risk appetite would squeeze defensive positioning harder than any yield level, just as a fresh supply shock would feed a rates market that has lost much of its positive beta to oil on moves lower and retained meaningful downside beta when oil moves higher. The trade-off is paying 1.7v over realised at the 7d on $BTC for exposure to both outcomes, against carrying spot beta into a week where long-end real yields set the discount rate and the narrow equity tape that crypto correlates to reports its two largest semiconductor names.
Positioning into the week
- $BTC front-end gamma into the CPI print: 7d ATM IV at 32.01v sits below the 30d at 34.66v and has cheapened from 34.5v a week ago, which places the one release capable of reopening October at the cheapest point on the curve.
- $ETH 7d optionality against delivered vol: implied of 41.5v against 41.9v realised on the IV-RV read leaves front-end $ETH convexity priced at what spot has already delivered, while the 30d leg still carries 7.1v over its own realised.
- Skew reversion from a call-bid extreme: $BTC 7d at -2.40v and $ETH 7d at -3.33v remain less put-bid than their 52-week medians of -4.40v and -3.88v, so a de-escalation that restores risk appetite would carry skew back towards last week’s call-bid levels long before it tests those medians.
- Perp carry compressing as open interest falls: $BTC funding at 5.6% annualised with OI down 1.9% to $29,333MM and $ETH funding down from 6.0% to 4.2% with OI off 6.9% to $18,999MM describes leverage leaving the market, which thins the liquidation fuel behind any CPI gap.
- Term premium at the long end as the dominant crypto input: with the 30y having traded 5.595% and 10y real yields up 18bps in a 2.8 standard-deviation week, the quality of any crypto rally depends on whether real yields fall alongside it.
Week ahead | 2026-10-12 | Derivatives via Laevitas